Landmark Supreme Court of India rulings, explained in clear, plain language.
Filter by Act / Section
Showing 2 of 2 judgments
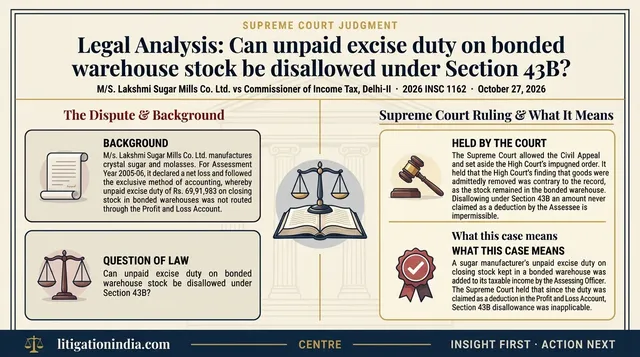
Can unpaid excise duty on bonded warehouse stock be disallowed under Section 43B?
M/S. Lakshmi Sugar Mills Co. Ltd. vs Commissioner of Income Tax, Delhi-II
The Supreme Court held that unpaid excise duty on closing stock kept in a bonded warehouse cannot be disallowed under Section 43B when the Assessee never claimed it as a deduction.
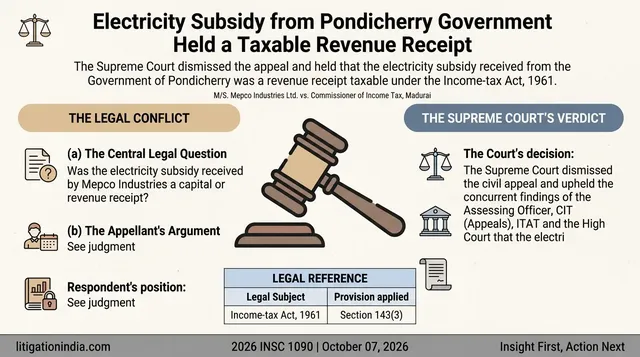
Was the electricity subsidy received by Mepco Industries a capital or revenue receipt?
M/S. Mepco Industries Ltd. vs. Commissioner of Income Tax, Madurai
The Supreme Court dismissed the appeal and held that the electricity subsidy received from the Government of Pondicherry was a revenue receipt taxable under the Income-tax Act, 1961.
You have reached the end — all 2 judgments loaded.