Landmark Supreme Court of India rulings, explained in clear, plain language.
Filter by Act / Section
Showing 2 of 2 judgments
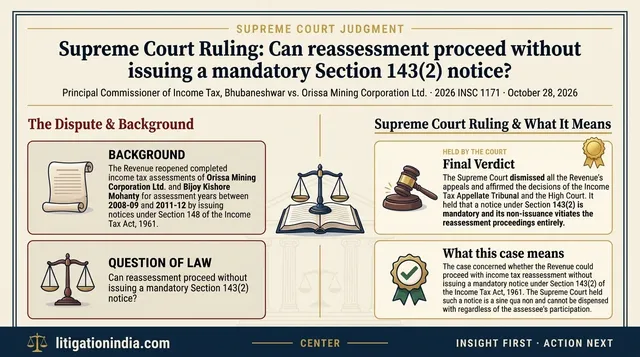
Can reassessment proceed without issuing a mandatory Section 143(2) notice?
Principal Commissioner of Income Tax, Bhubaneshwar vs. Orissa Mining Corporation Ltd.
The Supreme Court dismissed the Revenue's appeals, holding that a notice under Section 143(2) of the Income Tax Act, 1961 is mandatory for reassessment and cannot be dispensed with by the assessee's participation or Section 292BB.
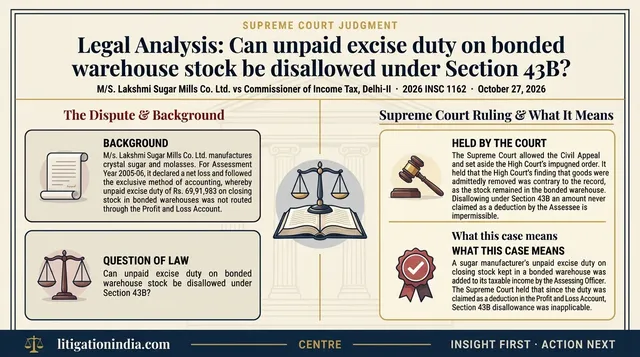
Can unpaid excise duty on bonded warehouse stock be disallowed under Section 43B?
M/S. Lakshmi Sugar Mills Co. Ltd. vs Commissioner of Income Tax, Delhi-II
The Supreme Court held that unpaid excise duty on closing stock kept in a bonded warehouse cannot be disallowed under Section 43B when the Assessee never claimed it as a deduction.
You have reached the end — all 2 judgments loaded.