Landmark Supreme Court of India rulings, explained in clear, plain language.
Filter by Act / Section
Showing 2 of 2 judgments
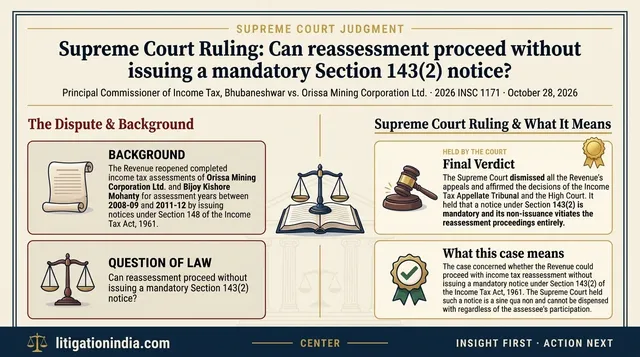
Can reassessment proceed without issuing a mandatory Section 143(2) notice?
Principal Commissioner of Income Tax, Bhubaneshwar vs. Orissa Mining Corporation Ltd.
The Supreme Court dismissed the Revenue's appeals, holding that a notice under Section 143(2) of the Income Tax Act, 1961 is mandatory for reassessment and cannot be dispensed with by the assessee's participation or Section 292BB.
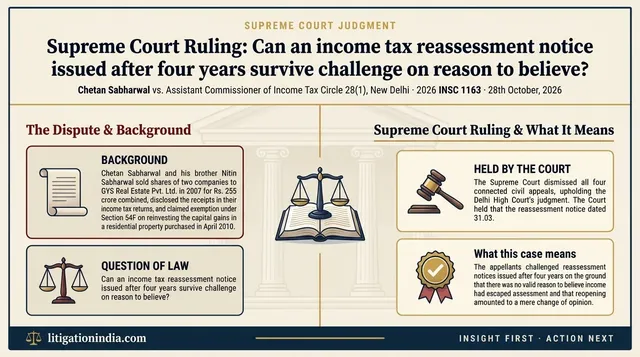
Can an income tax reassessment notice issued after four years survive challenge on reason to believe?
Chetan Sabharwal vs. Assistant Commissioner of Income Tax Circle 28(1), New Delhi
The Supreme Court dismissed the appeals and held that the reassessment notice dated 31.03.2015 was valid, as the Investigation Unit's report constituted tangible material with a live link to the belief that income had escaped assessment, and no case of change of opinion was made out.
You have reached the end — all 2 judgments loaded.