Full text of the judgment
Text extracted from M/s. New India Assurance Company Ltd. vs. M/s. Hemkund Duplex and Board Pvt. Ltd.. For the authoritative version refer to the Supreme Court of India's official website.
2026 INSC 1023
Reportable IN THE SUPREME COURT OF INDIA CIVIL APPELLATE JURISDICTION
Civil Appeal No. 7221 of 2025
M/s. New India Assurance Company Ltd.
… Appellant
versus M/s. Hemkund Duplex and Board Pvt. Ltd. … Respondent with
Civil Appeal No. 11416 of 2025
J U D G M E N T
SANJAY KUMAR, J 1. M/s. New India Assurance Company Ltd., the appellant in Civil Appeal No. 7221 of 2025, assails the order dated 19.11.2024 passed by the National Consumer Disputes Redressal Commission1, New Delhi, in Consumer Complaint No. 66 of 2011, whereby it was directed to pay a sum of ₹2,40,00,000/- to M/s. Hemkund Duplex and Board Pvt. Ltd., the respondent therein, with interest thereon within 45 days of the order, failing which the amount payable was to carry higher interest @ 12% per annum from the date of expiry of 45 days till the date of actual payment.
1 For short, ‘the NCDRC’ Digitally signed by babita pandey Date: 2026.09.21 17:11:35 IST Reason: Signature Not Verified
Further, it was directed to pay compensation of ₹3,00,000/- for deficiency in service, on account of inordinate delay in settling the claim, along with litigation costs of ₹1,00,000/-. While so, unsatisfied with the order dated 19.11.2024 of the NCDRC and the quantum of compensation awarded to it thereunder, the respondent filed Civil Appeal No. 11416 of 2025. 2. The claim put forth by the respondent, M/s. Hemkund Duplex and Board Pvt. Ltd., the complainant in Consumer Complaint No. 66 of 2011, was for compensation of ₹7,31,31,096.78, with interest @18% per annum, apart from other damages, on the strength of two fire insurance policies that it had with the appellant insurance company. 3. Parties are referred to as arrayed in Civil Appeal No. 7221 of 2025. 4. The respondent took over a sick unit in the year 2005 and took up its manufacture of paper boards, etc., ostensibly using waste paper, boards, Hessian bags, hay, medicine wrappers, packaging material, cuttings of egg trays and old waste, coloured and white paper cuttings, etc., as raw material. The factory of the respondent at Najibabad consisted of an open yard and three godowns, i.e., two pucca godowns and one tin shed. It insured its stock and buildings with the appellant under two separate fire policies. The fire policy for the stock was for a sum of ₹13,00,00,000/- and the coverage was from 30.12.2008 to 29.12.2009. The fire policy for the buildings, plant and machinery was for a sum of ₹14,00,00,000/- and the coverage was from 28.02.2009 to 27.02.2010.
5. While so, on 07.05.2009, at about 1.30 pm, a fire is stated to have broken out in the waste paper yard inside the factory of the respondent, resulting in damage to the raw material and to the tin shed. Anil Kumar, a supervisor, was stated to be the first person who saw the fire in the tin shed and told Gagandeep Singh, the Vice President of the respondent, who informed the fire brigade and the police. The fire brigade is stated to have arrived at around 2.30 pm. The appellant was also informed on the very same day. R.C. Bajpai was appointed by the appellant as a preliminary surveyor on 08.05.2009 and he carried out an inspection. On 09.05.2009, the respondent lodged its claim with the appellant. 6. However, by his report dated 24.06.2009, R.C. Bajpai stated that the case required meticulous investigation to rule out the possibility of a deliberate fire and hypothetical loss. Having said so, he tentatively assessed the net loss of the stock and building at ₹56,46,681/-. The appellant then brought in Royal Associates, an investigative and detective agency, which filed a report on 02.03.2010. It opined that the date and time of the fire seemed genuine, but the cause of the fire was not clear; the tin shed was in an isolated place inside the factory and workers rarely visited it; there was no chance of anybody throwing an ignited beedi/ cigarette in the godown, as smoking was prohibited inside the factory; even throwing of ignited material from outside the factory was remote, as it was covered with a roof and there was a boundary wall of sufficient
height around the factory; and there seemed to be no usable stock inside the tin shed. The fire station was informed one hour after the fire though it was just 06-07 kms away from the factory but the respondent did not bother to send someone. The appellant was advised to deal with the claim as per the terms and conditions of the policy in view of these findings. 7. The appellant appointed Aditi Consultants Pvt. Ltd. as the final surveyor. Final survey report dated 13.03.2010 was submitted by it. Therein, it noted that Anil Kumar, the supervisor, claimed to have seen the fire at 1.35 pm on 07.05.2009 and he informed Gagandeep Singh, the Vice President, on his mobile phone. Anil Kumar claimed that a hose pipe was plugged into the fire hydrant adjacent to the yard and attempts were made to extinguish the fire. Gagandeep Singh, the Vice President, claimed that he came to the waste paper yard immediately and on the way, he tried to call the fire brigade @ 101 from his mobile number but it did not go through. He then called one Anas in the office on his mobile and asked him to call the fire brigade using the landline. However, the landline was not working on that day. Gagandeep Singh claimed to have somehow traced out the mobile number of the fire brigade officer and sought help and, thereafter, the fire brigade arrived at the site. 8. Reference was made by Aditi Consultants Pvt. Ltd. to the fire brigade’s report dated 20.06.2009, wherein it was noted that, though the fire started at 13.35 hours on 07.05.2009, information was received by the
fire station from Gagandeep Singh only at 14.25 hours. The fire brigade arrived at the location at 14.36 hours. The distance from the fire station was stated to be 7 kilometers and the cause of the fire was unknown. The detailed description, as per the fire brigade’s report, reads to the effect that the fire was in the waste paper yard where the staff of the factory was sprinkling water through a hose pipe from a hydrant installed in the factory. It was noted that the respondent could not provide the cause for the fire but it was observed that there was no electric connection at the waste paper yard and, as such, the fire originating from a short circuit was ruled out; as smoking was prohibited, the possibility of the fire originating from a beedi/cigarette was also ruled out; there was a delay of one hour in informing the fire station; the tin shed had tilted and it was noticed in the depiction of the state of the shed when the fire brigade arrived. 9. It was observed by Aditi Consultants Pvt. Ltd that, ordinarily, when such a large quantity got burnt, the shed would have gotten destroyed and would have collapsed from the center, with sheets getting blown away, but the condition of the tin sheets did not depict such massive damage, as many of them had not even darkened. It was also noted that, as per the investigation, the shed was destroyed with the help of a JCB a few days prior to the fire. Further, substantial remnants of Hessian bags were noticed, but no record of the same were available in the books of accounts. It was, accordingly, concluded that the accurate cause of the
fire remained unestablished and no evidence had been adduced to hold that this was an accidental fire. Having said so, Aditi Consultants Pvt. Ltd computed the net loss for the damaged waste paper at ₹34,59,189/-. Therefore, with the net loss for the tin shed, computed at ₹11,50,534/-, the total loss was quantified at ₹46,09,722/-. It was, however, observed that the respondent had filed a claim which was substantially higher than the loss suffered as it had manipulated the books of accounts to inflate the claim, in violation of the condition in the insurance policy with regard to making a false declaration. The appellant was advised to deal with the claim as per the terms and conditions of the policy. 10. The appellant repudiated the respondent’s claim, vide letter dated 28.06.2010. Therein, it stated that the respondent had tried to manipulate the books of accounts to inflate the claim, in violation of Policy Condition No. 06. Referring to the survey report, the appellant stated that the tin shed had been broken down before the fire; the chance of the fire due to a short circuit was nil; the fire station was informed about one hour late, though it was just 6 kilometers away from the factory; and the cause of the fire was doubtful. It also asserted that the respondent was not able to sustain the loss claimed; the stock record was not proper; the yield reported was imaginary; and it could be safely concluded that the books of accounts were manipulated to take undue advantage, as the transactions were simply book entries, in clear violation of Policy
Condition No.8, which spoke of a false declaration made in support of a claim leading to forfeiture of the benefits due under the policy. 11. Faced with the aforestated facts, the NCDRC opined that as the cause of the fire was unknown, the onus was not upon the respondent to prove the cause therefor or the genuineness of the fire. Further, the NCDRC was of the opinion that there was no deliberate delay on the part of the respondent in informing the fire brigade. The NCDRC concluded that there was no reason to doubt the respondent’s claim and benefit had to be extended to it. It, accordingly, went on to assess the respondent’s claim on merits with regard to the stock, on the one hand, and the building, on the other. The claim in this regard, so far as the stock (waste paper) was concerned, amounted to ₹7.70 crore (affected stock being ₹9.50 crore, less the saved stock of ₹1.80 crore) and for the building, it was ₹0.75 crore. In all, the respondent’s claim was for ₹8.45 crore. However, the revised details of loss submitted by the respondent on 22.06.2009 indicated that 15,172.1291 metric tons of waste paper stock had been destroyed, valued at ₹4289.43 per metric ton, aggregating to a loss of ₹6,50,79,847/- along with damages quantified at ₹80,51,250/- in the context of the building, totaling to ₹7,31,31,897/-. 12. In the context of the claims made by the respondent, the appellant contended before the NCDRC that the respondent was incurring business losses and appeared to have been declaring profits by showing income
through speculation, not related to trade. Further, it pointed out that the working capital limit had been enhanced in August, 2008, whereby the stock level and debtors level increased abnormally, not in agreement with the books. Further, the stock levels reported in the stock statement were not reliable and it appeared that the books were being manoeuvred to avail huge limits and the transactions were just book entries. Various details were furnished by the appellant with regard to the accounts of the respondent. However, the NCDRC went on to assess the loss in relation to the stock and the building, resulting in its final directions, as set out supra. Aggrieved thereby, the appellant filed Civil Appeal No.7221 of 2025. With delay in refiling, the respondent filed Civil Appeal No.11416 of 2025. 13. By order dated 23.05.2025 in Civil Appeal No.7221 of 2025, this Court stayed the operation of the order passed by the NCDRC, subject to the appellant depositing a sum of ₹50,00,000/- with the Registry. This amount was directed to be placed in an interest-bearing fixed deposit with a nationalized bank for a period of six months with an auto renewal clause. 14. The first and foremost issue that requires to be addressed is whether the appellant was justified in repudiating the respondent’s claim at the threshold in its entirety. It is only if the appellant fails on this count that the need would arise for this Court to evaluate the assessment by the NCDRC of the loss allegedly suffered by the respondent in relation to its stock and building.
15. On the aforestated crucial preliminary issue, we find that the facts weigh heavily against the respondent. R.C. Bajpai, the preliminary surveyor, was highly critical of the respondent’s claims in his report dated 24.06.2009. He highlighted the fact that the respondent was constantly changing its stand as to the extent of the loss it had suffered, as it informed the media of a loss of ₹15 crore while a loss of ₹10 crore was reported to the appellant but the loss, as per the claim form, was ₹8.45 crore which was then reduced to ₹7.31 crore. He opined that Anil Kumar appeared to be a fabricated eyewitness. He noted that there was no electric connection or other possible cause for origin of the fire. He observed that there was no possibility of an ignited beedi/cigarette being the cause as the yard was located at an isolated place and the workers rarely visited it. He noted that mostly female labour was deployed at the yard for sorting out the material; that smoking was strictly prohibited inside the factory compound; and nobody was found smoking in the entire area. Further, he noted that there was no sign of heat or smoke on the tin (GI) sheets, except on the sheets at the back side of the yard. According to him, this confirmed that either there was no stacking of material in approximately 25% of the area or the stacking was to a very low height. Lastly, he noted that there was no conductor due to which the fire could have spread to the duplex bags stored at a distance of 20 to 25 feet, without having affected the grass in between, as the grass was found fresh at the time of his physical
verification. He also noted that, as per the video recording and the photographs taken at the time of the fire extinguishing operations, the respondent’s loss minimization efforts were not bonafide as it was found that its employees were sprinkling water either on the roof or on the ground outside the yard but not on the fire. He also noted that, had 15,000 metric tons of paper been burnt in that fire, it would have been more devastating and would have required far more efforts to extinguish it, as the total structure of the yard would have collapsed due to intense heat. The other issues flagged by him in the report pertained to the irregularities in bookkeeping and the accounts as regards the stock and sales. His conclusion was that there were abnormalities regarding the cause of fire, collapse of the shed and serious deviations shown by the substantial decrease in raw material consumption and abnormal increase in yield. Moreover, on correlation of the records submitted by the respondent and the actual physical stocktaking, he found that the stock was created in the books which did not have actual corresponding existence. He said the quantity of stock found during physical verification was far less than the book stock and even the purchase bills submitted to substantiate the loss were a total mismatch, being inconsistent with the material found on verification. Therefore, considering the several abnormalities in the case, the surveyor concluded that it needed to be investigated meticulously to rule out any possibility of a deliberate fire and a hypothetical loss.
16. The report dated 02.03.2010 of Royal Associates, the investigative and detective agency, was equally adverse to the respondent. It was noted therein that the respondent could not tell the cause of the fire and as per the information gathered from the workers and upon inspection of the factory, it was found that the tin shed was situated in an area away from the working place and no one used to routinely visit the tin shed. It noted that, as smoking was strictly prohibited in the factory, there was no chance of someone throwing ignited material. The tin shed was far away from the working place and throwing of such material from outside the factory was not possible. As there was no electricity connection also in the tin shed, it was opined that the cause of the fire was doubtful. Further, the agency noted that there seemed to have been no useable stock in the tin shed, as the factory workers stated that only unusable stock of waste paper was stored therein. Some of the workers told the agency that such stock was lying in the godown from even before the taking over of the factory by the new management. Some said that, after segregation, unusable raw material was stored in the tin shed. According to the workers, routinely, stock was unloaded in the two pucca godowns and from there, after segregation, unusable raw material was shifted to the tin shed and usable raw material remained in the pucca godowns, wherefrom it would be shifted to the pulp section as per requirement. The agency also noted that the affected yard was a waste paper yard and had a huge
stacking of Hessian bags and the fire mostly concentrated on the area where the said bags were stored. However, during the physical verification it was observed that the said Hessian bags had particles of hay and bagasse (byproduct of sugarcane crushing). Behind this stock, a huge heap of cuttings of medicine wrappers and cuttings of egg trays and old waste, coloured and white paper cuttings, were found. Further, while verifying the stock, it was noted that plastic bags and pieces of rope, in good quantity, were also found, which were not part of the raw material. Moreover, the material was found to be very old and it could be seen that it had been stored since a long time as even cobwebs were observed. The agency opined that this was dead material and rejected stock. It attempted to correlate the stock with the purchase bills but failed, as most of the stock did not match the description in the purchase bills. Discrepancies were observed upon inspection of the burnt portion of the factory. Tin sheets on the roof of the affected yard were not bent out of shape by the fire. It was observed that all iron angles of the roof were tilting in a particular angle and were not bent out of shape by the fire. No impact of burning, such as black spots, etc., were found on the tin sheets. The agency also noted that the fire station had been informed about one hour after the fire broke out and the respondent had tried to explain this by claiming that the landline number of P & T was not working and 101 could not connect from a mobile phone. The agency, however, observed that fire
station was just 6-7 kms away from the factory but the respondent had not bothered to send someone to the fire station. The appellant was accordingly advised to deal with the claim as per the terms and conditions of the policies, as the intention of the respondent was found doubtful. 17. The final report dated 13.03.2010 of Aditi Consultants Pvt. Ltd. was just as damaging to the respondent. Its claims were noted, whereby it came down from ₹10 crore to ₹8.45 crore and then to ₹7.31 crore. It was noted that there was no possibility of any careless throwing of an ignited beedi/cigarette as the yard was isolated and workers rarely visited it. Mostly female labour was deployed at the yard for sorting of material, but they too were not visiting the yard for a few days prior to the fire. Smoking was strictly prohibited inside the factory. No sign of heat or smoke was seen on the tin (GI) sheets except on the sheets at the back side of the yard. This confirmed that either there was no stacking of material in approximately 25% of the area or the stacking was of very low height. There was no conductor of fire due to which the fire could have spread to the duplex bags stored at a distance of 20 to 22 feet without having affected the grass in between, which was found to be fresh at the time of the inspection. There was an abnormal delay in informing the fire station and a suspicious approach in extinguishing the fire. It was pointed out that the structure had not collapsed after the fire and investigation was needed to rule out a deliberate fire. It was noted that there was huge stock of fully
burnt Hessian bags and it was observed that the same were not part of the raw material but no justification was given by the respondent for such storage. It was also noted that the books of accounts could not be correlated with the stock in the yard and the stock of about 12,500 metric tons was mostly book stock and was not in existence. It was opined that the material stored in the tin shed/yard was dead and obsolete stock. It was also noted that there was an abnormal increase in yield and from May, 2008, the yield of 87% had increased to 95%, i.e., an increase of 8% continuously for the onward period, which has resulted in accumulation of huge book stock. Having studied the trend of other paper mills and the trend of the respondent’s paper mill, it was opined that 8% increase was abnormal. It was concluded that abnormalities regarding the cause of the fire, collapse of the shed and serious deviations shown by substantial decrease in raw material consumption and abnormal increase in yield were evident. The appellant was accordingly advised to deal with the case as per the terms and conditions of the policy. 18. At this stage, we may note that the requirement of an insurance company taking recourse to a licensed surveyor, when an insurance claim is raised against it, is traceable to Section 64UM of the Insurance Act, 19382. Prior to its amendment in 2015, Section 64UM(2) read thus:
2 For short, 'the Act of 1938'
‘S. 64UM(2): No claim in respect of a loss which has occurred in India and requiring to be paid or settled in India equal to or exceeding twenty thousand rupees in value on any policy or insurance, arising or intimated to an insurer at any time after the expiry of a period of one year from the commencement of the Insurance (Amendment) Act, 1968, shall, unless and otherwise directed by the Authority, be admitted for payment or settled by the insurer unless he has obtained a report, on the loss that has occurred, from a person who holds a license issued under this section to act as a surveyor or loss assessor (hereafter referred to as "approved surveyor or loss assessor"). Provided that nothing in this sub-section shall be deemed to take away or abridge the right of the insurer to pay or settle any claim at any amount different from the amount assessed by the approved surveyor or loss assessor.’ The ‘Authority’ referred to in Section 64UM of the Act of 1938 is the ‘Insurance Regulatory and Development Authority of India’. 19. In turn, Section 64UM(1-A) of the Act of 1938 states that every surveyor and loss assessor shall comply with the code of conduct in respect of their duties, responsibilities and other professional requirements as may be specified by the regulations made by the Authority. Section 2(1)(g) of the Consumer Protection Act, 1986, applicable presently, defined ‘deficiency’ as any fault, imperfection, shortcoming or inadequacy in the quality, nature and manner of performance which is required to be maintained by or under any law for the time being in force or has been undertaken to be performed by a person in pursuance of a contract or otherwise in relation to any service. 20. We may now note the decisions of this Court in the context of the aforestated statutory provisions. In New India Assurance Company
Limited vs. Pradeep Kumar3, this Court held that although the assessment of loss by an approved surveyor is a pre-requisite under Section 64UM(2) for settlement of a claim of twenty thousand rupees or more by an insurer, the surveyor's report is not the last and final word, as it is not sacrosanct or conclusive and could be departed from. It was observed that an approved surveyor's report may be the foundation for settlement of a claim by an insurer in respect of the loss suffered by an insured but such report is neither binding upon the insurer nor the insured. This was in keeping with the proviso to Section 64UM(2) above. 21. This edict was affirmed in Khatema Fibres Limited vs. New India Assurance Company Limited and another4 and the factors that have to be established to bring the actions of a surveyor within 'deficiency in service' were summed up. It was held that the Act of 1938, while assigning an important role to the surveyor, cast an obligation upon him under Section 64UM(1-A) thereof to comply with the code of conduct. Two things flow therefrom - (i) that a surveyor is governed by a code of conduct, the breach of which may give rise to an allegation of deficiency in service; and (ii) that the discretion of the insurer to reject the report of the surveyor, in whole or in part, cannot be exercised arbitrarily or whimsically and that, if so done, there could be an allegation of deficiency in service.
3 (2009) 7 SCC 787 4 (2023) 15 SCC 327
22. Earlier, in Sri Venkateswara Syndicate vs. Oriental Insurance Company Limited and another 5, this Court had observed that there is no prohibition in the Act of 1938 for appointment of a second surveyor by an insurance company but, while doing so, the said company has to give satisfactory reasons for not accepting the report of the first surveyor and the need to appoint a second surveyor. It was observed that the scheme of Section 64-UM(2), (3) and (4) showed that an insurer could not appoint a second surveyor as a matter of course. It was observed that the insurer must specify cogent reasons, without which it would not be free to appoint a second surveyor so as to get a report which would satisfy its interest. 23. However, in the present case, R.C. Bajpai, the first surveyor, had recorded that the abnormalities of the case needed to be investigated meticulously to rule out the possibility of a deliberate fire and hypothetical loss. His tentative assessment of the loss was subject to that finding. He had, therefore, advocated for further investigation in clear terms. 24. Notably, in United India Insurance Co. Ltd. and others vs. Roshan Lal Oil Mills Ltd. and others6, this Court had observed that the NCDRC was not justified in ignoring the report submitted by the joint surveyors appointed under Section 64-UM(2) of the Act of 1938. The report contained a detailed account of the factors on the basis of which
5 (2009) 8 SCC 507 6 (2000) 10 SCC 19
the joint surveyors came to the conclusion that there was no loss caused on account of the fire and it was on this basis that the claim was rejected. This Court observed that the said report was an important document which was placed before the NCDRC but the NCDRC, curiously, had not considered it. This Court further held that as the claim of the insured was repudiated by the insurance company on the basis of the joint survey report, non-consideration of that important document resulted in a serious miscarriage of justice, which vitiated the judgment passed by the NCDRC. 25. Pertinently, we find that the respondent acknowledged receipt of the reports of the two surveyors and the investigating agency in its Consumer Complaint No. 66 of 2011 but, except for baldly stating that the surveyors and the investigator gave negative reports and asserting its innocence in the context of the maintenance of the stock taking and books of accounts, the respondent did not point out any specific deficiency on the part of the surveyors, in terms of the statutory requirement. Despite the same, the NCDRC simply brushed aside both the surveyors’ reports, wherein the genuineness of the respondent’s claims was negated on facts. 26. In New India Assurance Company Limited and others vs. Mudit Roadways7, this Court considered an insurance claim arising out of a fire accident, wherein multiple survey reports suggested different causes for
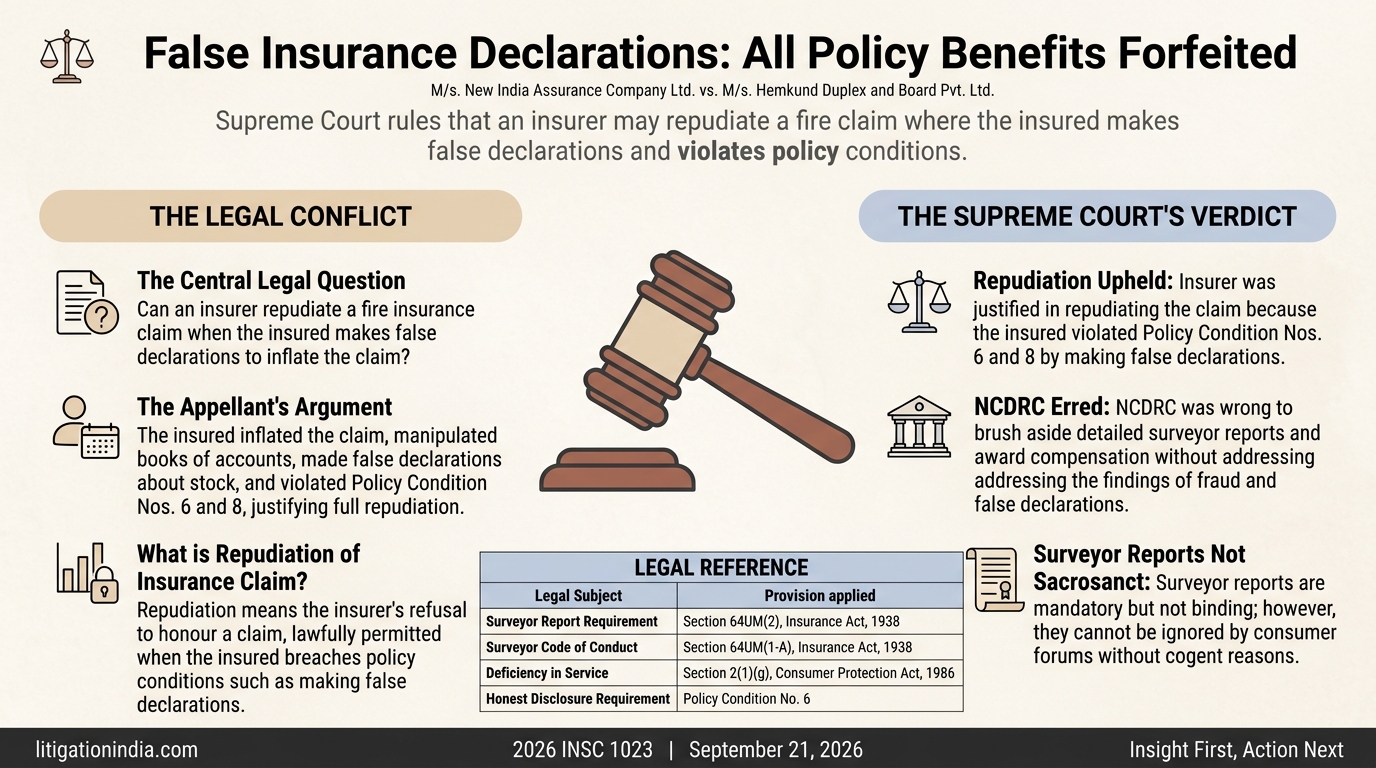
7 (2024) 3 SCC 193
the fire, presenting a perplexing conundrum. The NCDRC had placed reliance on the judgment of this Court in Canara Bank vs. United India Insurance Company Limited and others8, wherein it was observed that as long as the insured is not the person who caused the fire, the insurance company cannot escape its liability in terms of the policy. It was, therefore, declared that where the precise cause of the fire, i.e., whether it was attributable to a short circuit or any other factor, could not be ascertained it was immaterial as long as the claimant was not the instigator of the fire. Thereafter, in Orion Conmerx Private Limited vs. National Insurance Company Limited9, this Court observed that, once it is established that loss was caused due to a fire but there was no allegation or finding of fraud or that the insured was the instigator of the fire, the cause of the fire would be immaterial and it would have to be assumed and presumed that the fire was accidental and the loss would fall within the ambit and scope of the insurance policy. In effect, if there is reasonable cause to suspect that the insured may have been the instigator of the fire, the claim put forth by such insured may, on facts, be liable to be denied on that ground. 27. In that regard, the respondent placed reliance upon a police report, wherein a Sub-Inspector stated that he had learnt that there was a sugarcane field behind the respondent’s factory wherein, after reaping the
8 (2020) 3 SCC 455 9 (2026) 5 SCC 445
harvest, the labour had lit a fire and there was a possibility that due to the direction of the breeze, a spark landed in the waste paper yard. This was supported by the affidavit of one Kailash Chandra, who claimed that he owned a sugarcane field behind the respondent’s factory. Therein, he stated that after reaping the harvest, the stubble was set on fire at 12 noon on 07.05.2009. He stated that there was a possibility that a spark from the fire could have reached the waste paper yard. However, there is no evidence of the distance between Kailash Chandra’s sugarcane field and the respondent’s factory. Further, the photographs relating to the fire lit in Kailash Chandra’s field show a patch of burnt grass surrounded by green grass and the magnitude of the fire does not appear to be significant. 28. Significantly, it has also been brought on record by the reports of the surveyors and the investigative agency that no bonafide attempt was made by the respondent or its employees to put out the fire. Though the fire was detected at 1.35 pm on that day, no sincere effort was made to summon a fire engine immediately. The fire station was just 06-07 kms away and the fire engine could reach within a span of 11 minutes after being called. No explanation was offered as to why Gagandeep Singh, the Vice President, who would have had a vehicle at the factory, did not send someone either by that vehicle or by an employee’s two-wheeler to inform the fire station. Admittedly, the fire brigade was informed 50 minutes after the fire broke out. Further, the reports also record that the fire-minimization
efforts by the employees of the respondent were not sincere as they merely sprinkled water either on the roof or on the ground but not on the fire itself. These are important factors that weigh against the respondent in the context of the fire being a genuine one and sincere efforts being made to fight the fire. Had it been so, these delaying tactics would not have been adopted. The damage to the tin sheets or rather, the lack of it, and the lack of damage to the main structure of the tin shed also speak of the nature of the fire and its extent. 29. The finding that the fire was mostly concentrated around the area where Hessian bags were stored adds to the suspicion of arson, as there was no account of these Hessian bags having been purchased as raw material in such large quantities. Though the respondent attempted to project in its complaint case that Hessian bags and all the other material found there were raw material, the final surveyor recorded that it was not so and when asked about the storage of these bags, the respondent had no justification to offer. Further, it was found that the material was very old as cobwebs were also present. The surveyor recorded that, during the firefighting operations, the branch manager of the appellant reached there and requested the respondent to increase the pressure of water from the hydrant pipe and asked him to utilize more hydrants so as to control the fire, but it was only 20 minutes after his request, that the respondent agreed to do so. It was only on the appellant's consistent requests that
arrangements were made to increase the water pressure. The other hydrant was used only after the fire brigade reached there. 30. Further, the report dated 02.03.2010 of Royal Associates notes that, as per the statement of Rajiv Aggarwal, General Manager (Finance) of the respondent, and Gagandeep Singh, its Vice President, the tin shed had fallen down due to the fire and they had to call the JCB to lift the tin sheets so that the raw material underneath, which was on fire, could be doused with water. However, Shamin, the owner of the JCB, got his statement recorded that he sent the JCB to the respondent’s factory to break down the tin shed before the fire incident. This statement of the JCB’s owner was supported by the workers at the respondent’s factory and also by Narinder Kumar and Anil Kumar, who were nearby shopkeepers. They stated that the owner of the factory had called for the JCB to get the tin shed broken down before the fire incident. The investigative agency, accordingly, noted that the tin sheets were not lifted by the JCB, as claimed by the respondent, but the tin shed was broken down earlier with the JCB's assistance. 31. In any event, apart from the possibility of arson or, at the very least, the respondent’s lack of sincerity in fighting the fire, there are other factors which decisively tilt the balance against it, viz. the breach of the policy conditions. In that regard, Policy Condition No. 6 of the fire insurance policies issued by the appellant to the respondent reads as follows:
‘6.(i) On the happening of any loss or damage the insured shall forthwith give notice thereof to the company and shall within 15 days after the loss or damage, or such further time as the company may in writing allow in that behalf, delivered to the company. (a) A claim in writing for the loss or damage containing as particular an account as may be reasonably practicable of all the several articles or items or property damaged or destroyed, and of the amount of the loss or damage thereto respectively, having regard to the value at the time of the loss or damage not including profit of any kind. (b) Particulars of all other insurances, if any. The insured shall also at all times at his own expense produce, procure and give to the company all such further particulars, plans, specification books, vouchers, invoices, duplicates or copies thereof, documents, investigation reports (internal/external), proofs and information with respect to the claim and the origin and cause of the loss and the circumstances under which the loss or damage occurred, and any matter touching the liability or the amount of the liability of the company as may be reasonably required by or on behalf of the company together with a declaration on oath or in other legal form of the truth of the claim and of any matters connected therewith. No claim under this policy shall be payable unless the terms of this condition have been complied with.’ Policy Condition No. 8 of the policies reads as under: - '8. If the claim be in any respect fraudulent, or if any false declaration being made or used in support thereof or if any fraudulent means or devices are used by the Insured or anyone acting on his behalf to obtain any benefit under the policy or if the loss or damage being occasioned by the willful act, or with the connivance of the Insured all benefits under this policy shall be forfeited.’ 32. On facts, we find that the above two conditions of the insurance policies were clearly breached by the respondent. Policy Condition No. 6 required the respondent to make an honest and full disclosure of all relevant aspects while Policy Condition No.8 posited that it make no false declarations. However, the misstatements made by the management of the respondent, referred to hereinbefore, categorically demonstrate that they willfully resorted to making incorrect factual statements to buttress
the respondent’s insurance claim. If an insured makes false averments to bolster its claim, contrary to the policy conditions, the insurer would be lawfully entitled to reject such claim on that ground without further ado. In this regard, we may also note that the final surveyor recorded the statements of workers/labour at the respondent’s factory. One Kamal Singh, Supervisor, stated that the raw material was unloaded into the two pucca godowns routinely and it was not stocked in the tin shed which had caught fire. He further stated that the raw material was directly shifted to the pulp section from the pucca godowns only. These statements were directly contrary to those of Gagandeep Singh, the Vice President, and Rajiv Aggarwal, the General Manager, who had said that unloaded raw material was stocked in the tin shed. The statements of the workers/supervisors showed that only waste material which was unusable was stocked in the tin shed and this was the practice since before the factory was taken over by the new management in 2005. They also confirmed that, after taking over the factory, the new management did not unload the raw material into the tin shed and did not lift any raw material from the tin shed. This evidence, which was not even challenged by the respondent in its complaint case, clearly demonstrates that false declarations were made on its behalf by Gagandeep Singh, its Vice President, and Rajiv Aggarwal, its General Manager, to the effect that usable raw material was stocked in the tin shed that caught fire, laying
foundation for the insurance claim. On the other hand, the statements of the workers/labour, supported by the finding of the surveyor that the burnt material was very old and with cobwebs, confirming its vintage, put it beyond the pale of doubt that a false claim was sought to be projected by the respondent by declaring that usable raw material was stocked in the burnt tin shed and not the unusable scrap which had accumulated there since before the new management took over the factory. Danish and Sandeep Shami, Accountants, confirmed the version of the workers that only unusable waste paper, after segregation, was stored in the tin shed and such segregated unusable waste paper had been destroyed in the fire. Sandeep Shami also confirmed that the said stock of unusable waste paper used to be stored in the tin shed from before the factory was taken over by the new management. All of them confirmed that the said stock had been lying in the tin shed for a long time. 33. The surveyor also found that the respondent’s raw material consumption-sales ratio had reduced abnormally, as reflected by the figures for 2007-08 when compared with 2008-09. The raw material consumption during 2007-08 was 310.25 lakh metric tons while the same shot up to 429.51 lakh metric tons for the year 2008-09. Surprisingly, the sales for the year 2007-08 stood at 960.48 lakh, which rose to 2,226.38 lakh during 2008-09. During the year 2007-08, the raw material to sales percentage was 32.30%, which fell drastically to 19.29% for the year
2008-09. The surveyor recorded that this variation needed an in-depth investigation and scrutiny as it could be the main reason for the huge book stock without correlation to the actual raw material on the ground. The surveyor’s report dated 13.03.2010 recorded the following abnormalities: The tax audit report indicated that no stock register was maintained by the respondent. Further, no stock movement register was found and it was found that the respondent reported the consumable stores level at ₹278.58 lakh from November, 2008 to March, 2009, which was held to be surprising. No records were available to verify how the consumable stocks were arrived at. Further, it was found that the respondent was producing a single item but no standard production mix could be detected from the consumption of chemical and waste paper, as recorded in the books. Consumption recorded in the books was found to be arbitrary so as to maintain book stocks and profitability. The surveyor opined that the respondent was recording arbitrary consumption in the stock records; there was no system of recording/weighing the waste paper at the time it was loaded on the conveyor; and the yield reported was imaginary. These were all false assertions made by the respondent to press its claim. 34. In the light of the above facts, leaving aside the strong possibility that this was not an accidental fire or, at the very least, it was not a fire that the respondent genuinely tried to put out, the repudiation of the respondent’s claim by the appellant, on the ground that Policy Condition
Nos. 6 and 8 stood violated, was clearly sustainable. The NCDRC was not justified in brushing aside the findings recorded in the two surveyors’ reports and in holding, without basis, that there was no delay on the part of the respondent in informing the fire station. Similarly, there was no basis for the NCDRC to have given a clean chit to the respondent, whereupon it undertook assessment of the loss allegedly suffered by it and in quantifying the same, far in excess of the quantification by the surveyors. 35. Civil Appeal No. 7221 of 2025 is, accordingly, allowed setting aside the order dated 19.11.2024 passed by the National Consumer Dispute Redressal Commission, New Delhi, in Consumer Complaint No. 66 of 2011. In consequence, Civil Appeal No. 11416 of 2025 filed by the respondent shall stand dismissed. Registry shall return to the appellant the suitor’s fund amount and the sum of ₹50 lakh deposited by it, along with the interest accrued thereon, under proper acknowledgement and as per due procedure. In the circumstances, parties shall bear their own costs.
..............................., J. SANJAY KUMAR
..............................., J. SANJEEV SACHDEVA September 21, 2026 New Delhi.