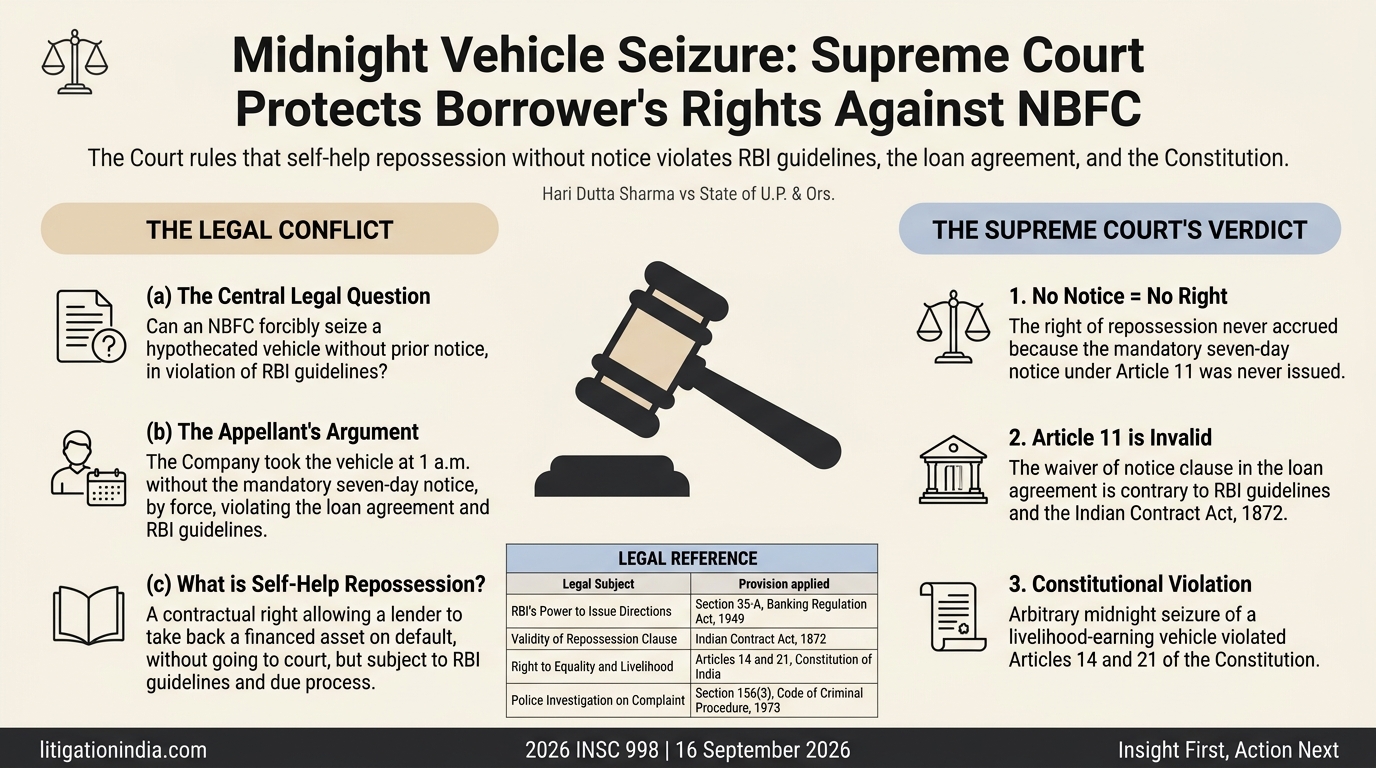
Full text of the judgment
Verbatim text extracted from the reported judgment in Hari Dutta Sharma vs State of U.P. & Ors.. For the authoritative version, refer to the Supreme Court of India's official website.
2026 INSC 998 1
REPORTABLE
IN THE SUPREME COURT OF INDIA CIVIL APPELLATE JURISDICTION
CIVIL APPEAL NO(S). OF 2026 (@ S.L.P. (C) NO(S). OF 2026) (@ DIARY NO. 10952 OF 2026)
HARI DUTTA SHARMA … APPELLANT VERSUS STATE OF U.P. & ORS. … RESPONDENTS
J U D G M E N T ALOK ARADHE, J. 1. Delay condoned. 2. Leave granted. 3. A loan may create a debt, and a debt may confer upon the financier a right to recover what is due; but the manner in which that right is exercised is not without significance. The present appeal brings before this Court the contest between the right to recover a secured debt and the right of the borrower to have that recovery undertaken within the bounds of law. 4. This appeal is directed against the Order dated 04.04.2025 passed by the High Court of Judicature at Allahabad by which the writ petition preferred by the appellant was dismissed. FACTS 5. Facts giving rise to the filing of this appeal lie in narrow compass. On 25.03.2019, the appellant obtained a commercial vehicle loan Digitally signed by KAPIL TANDON Date: 2026.09.16 16:50:11 IST Reason: Signature Not Verified
2
from Cholamandalam Investment and Finance Company Limited (the Company) for his truck namely, Tata SFC 407 bearing registration No. UP-16-GT-0449. Out of the sanctioned amount of loan of Rs.10,40,080.75 (Rupees Ten Lakh Forty Thousand Eighty Rupees and Seventy-Five Paise only) a sum of Rs.9,36,000/- (Rupees Nine Lakh Thirty-Six Thousand only) was disbursed. The amount of loan was to be repaid in 75 monthly instalments, and was secured by hypothecation of the vehicle. On 12.06.2021, a further sum of Rs.1,04,080.75 (Rupees One Lakh Four Thousand Eighty and Seventy-Five Paise only) was extended as a supplementary loan. 6. The appellant failed to honour the repayment commitments and did not pay the amount of instalments due under the loan agreement. A recall-cum-demand notice dated 17.01.2022 calling upon the appellant to discharge his outstanding liability was issued. The appellant continued to make defaults in repayment of loan amount. The Company repossessed the vehicle and issued a pre-sale letter on 13.06.2022 to the appellant. The appellant paid a sum of Rs. 86,726/- (Rupees Eighty-Six Thousand Seven Hundred Twenty-Six only) and assured to regularise the loan account. Thereupon, the vehicle was released.
3
7. The appellant again did not pay the instalments due under the loan agreement. Thereupon, notices dated 07.07.2022 and 22.12.2022 were issued granting an opportunity to the appellant to clear the outstanding dues or to surrender the hypothecated asset. The appellant was further informed that upon such surrender of the vehicle the same shall be sold “on as is where is” basis and the sale proceeds will be appropriated towards the amount under the loan agreement. According to the Company, the appellant even after issuance of said notices, did not repay the amount of the loan, thereupon, a pre-seizure notice dated 09.04.2023 was sent to the SHO Police Station, Ayodhya Cantt. 8. According to the appellant, on 09.04.2023, while the vehicle stood parked after making delivery of goods at a consignor’s godown under CCTV surveillance at Ayodhya, four unidentified persons broke the vehicle’s steering lock at about 1:00 a.m. and drove it away. The vehicle was repossessed without issuing any notice to the appellant. The appellant lodged a lost article Report and an e- FIR on the same day. No action was taken on the complaint of the appellant for tracking the said vehicle. The appellant thereupon submitted a complaint on 08.09.2023 to the Superintendent of Police, Ayodhya.
4
9. On 30.09.2023, the appellant received a legal notice from the Company disclosing that since the appellant had failed to make repayment of the amount of loan due, the possession of the vehicle has been taken and the same has been sold on 31.08.2023. It was further stated in the notice that amount payable by the appellant as on 31.08.2023 was Rs.5,71,914/- (Rupees Five Lakh Seventy One Thousand Nine Hundred Fourteen only) and a sum of Rs.4,50,000/- (Rupees Four Lakh Fifty Thousand only) was recovered as sale proceeds. The appellant was informed that he was required to pay a further sum of Rs.1,25,571/- (Rupees One Lakh Twenty Five Thousand Five Hundred Seventy One only). 10. The appellant, thereupon, filed a complaint under Section 156(3) of the Code of Criminal Procedure before the Chief Judicial Magistrate, Ayodhya which was dismissed on 23.09.2024 on the ground that the vehicle had been confiscated for default. 11. The appellant filed a writ petition before the High Court. The Division Bench by an Order dated 04.04.2025, noted that the vehicle had already been sold on 31.08.2023 and held that the appellant had belatedly approached the Court. It was found that the appellant defaulted in the payment of instalments of the loan. Accordingly, the writ petition was dismissed.
5
SUBMISSIONS 12. Learned counsel for the appellant submitted that the High Court fell into error in non-suiting the appellant on the ground of delay. It was further submitted that the High Court ought to have appreciated that the action of the Company in taking possession of the vehicle was in stark violation of Article 11 of the Loan Agreement, which mandated seven-days’ prior notice. It was further submitted that a financier’s right of self-help repossession under the hypothecation agreement cannot be exercised by force, deceit or in violation of the terms of the Agreement. It was pointed out that, even after the sale of the vehicle, the appellant was continuously visited with traffic challans. 13. On the other hand, learned counsel for the Company submitted that the appellant was a chronic defaulter, as is reflected in the consolidated statement of account. It was further submitted that on an earlier occasion, on an identical default, repossession of the vehicle was forestalled only upon making part- payment of the loan amount. It was also submitted that pre-seizure intimation, inventory list, post-seizure intimation and pre-sale notice were duly furnished to the police and the appellant. It was contended that the vehicle was sold for Rs.4,50,000/- (Rupees
6
Four Lakh Fifty Thousand only) which was fair and in accordance with the terms of the loan agreement. ANALYSIS 14. We have considered the rival submissions and have perused the record. 15. It is well-settled in law that a financier’s right to take possession of the financed vehicle in the first instance, is a matter of contract, where an agreement confers such a right, there is no legal impediment to its exercise unless the contract is unconscionable or opposed to public policy1. Such clauses of self-help repossession are not, in themselves, an evil to be eradicated: they are what make it commercially feasible for institutions to extend credit, against the security of the very asset financed, to borrowers of modest means, truck operators and small transporters among them, who possess no conventional collateral and would otherwise remain outside the reach of institutional finance. But precisely because this right operates as an alternative to recovery through courts or tribunals, outside the supervision of a court at the first instance, it must be construed with great circumspection; left unchecked, it is capable of being
1 Orix Auto Finance (India) Ltd., v. Jagmander Singh and Anr., (2006) 2 SCC 598 and Sundaram Finance Limited and Anr. v. T. Thankam, (2015) 14 SCC 444.
7
read as an unbridled licence to seize property by stealth, by force or in the dead of night, converting a facility meant to promote financial inclusion into an instrument of oppression against the very class it was designed to serve. 16. Section 35-A of the Banking Regulation Act, 1949, empowers the Reserve Bank of India (RBI) to issue directions to the banking companies. The said power can be exercised in four contingencies, namely: (i) public interest; (ii) interest of banking policy; (iii) interests of depositors; and (iv) interests of the banking companies. The directions issued under Section 35-A possess a statutory force and are binding on the banking companies2. 17. The RBI, on 05.05.2003, with an object to protect the rights of citizens dealing with the Non-Banking Financial Company (NBFC)/Banks and to curb the arbitrary action on the part of such institution in resorting to alternate modes of recovery without approaching the courts or tribunals, issued Guidelines on ‘Fair Practices Code for Lenders’. The said guidelines were issued on the basis of recommendations made by Working Group on Lenders’ Liability Laws constituted by the Government of India. The banks/financial institutions were advised to adopt the said Guidelines and frame the Fair Practices Code duly approved
2 Internet and Mobile Association of India v. Reserve Bank of India (2020) 10 SCC 274.
8
by their Board of Directors. Paragraph (v)(c) of the said Guidelines provides that in the matters of recovery of loans, the lenders should not resort to undue harassment viz., persistently bothering the borrowers at odd hours, use of muscle power for recovery of loans etc. 18. Another set of Guidelines were issued on 21.11.2005, by the RBI which covered a wide area pertaining the rights of the customers, right to privacy and confidentiality, practice of debt collections, redressal of grievances and monetary systems to be implemented by Banks. Thereafter, on 28.09.2006, the Guidelines on Fair Practices Code for NBFCs were issued, wherein, it was reiterated that NBFCs should not resort to undue harassment viz. persistently bothering the borrowers at odd hours and use of muscle power for the recovery of loans, etc. 19. A two-Judge Bench of this Court had occasion to consider the 2003 Guidelines in ICICI Bank Ltd. v. Prakash Kaur and Ors.3 where registration of First Information Report against the recovery agents of ICICI Bank Ltd. for forcibly taking possession of a vehicle fell for consideration. This Court emphasised that the rights of financial institutions in employing alternate means of recovery other than the due process of law either through courts
3 (2007) 2 SCC 711
9
or tribunals has to be viewed from the angle of common man no less than that of financial institutions. It was observed that once a loan is taken and there is a default, the witch-hunt begins and the bank is an aggressor whereas the public is the victim. It was also noted that financial institutions employ recovery agents to trace the defaulter and recover the amounts of loans and a person’s self-respect and stature in the society is immaterial to such an agent. This Court held in terms which bear reiteration that ours is a country governed by rule of law and recovery of loans or seizures of vehicles could only be made through the legal means and the banks cannot employ ‘goondas’ to take possession of the vehicles by force. The court enumerated the suggestions to be followed by the financial institutions/banks for recovery of the amount and seizure of the vehicle and noted that even though the RBI had issued the Guidelines on 21.11.2005 which remains only on paper and is not being followed. 20. Following Prakash Kaur (supra), and having regard to the rising volume of disputes and litigations arising from conduct of recovery agents and to the reputational risk such conduct visits upon the banking sector as a whole, the RBI, issued successive Master Circulars, Guidelines and Clarifications, on 24.04.2008, 24.04.2009, 01.07.2009, 01.07.2010, 01.07.2011, 26.03.2012,
10
02.07.2012, 18.02.2013, 01.07.2013, 01.07.2014 and 01.07.2015, to all NBFCs and the Scheduled Commercial Banks. These instruments taken together address the following aspects: (i) formulation and display of Fair Practices Code duly approved by the Board of Directors, (ii) right of customers and their right to privacy and confidentiality, (iii) practice of collection of debts, (iv) methods of recovery to be followed by recovery agents and their training, (v) provisions to be contained in the repossession clauses, (vi) the need of creating a grievance redressal system in relation to complaints against the banks and its recovery agents; and (vii) utilisation of credit counsellors. 21. A careful reading of the Master Circulars, the Guidelines and the clarifications issued by the RBI, discloses the following position which we consider necessary to set out for the guidance of financial institutions and of the Courts dealing with similar controversies in future: (i) Lenders shall not, in the recovery of loans, resort to undue harassment of borrowers, whether by persistently bothering them at odd hours or by the deployment of muscle power.
11
(ii) Seizure of a vehicle can only be effected through lawful means; banks and financial institutions cannot employ ‘goondas’ to take possession by force. (iii) Banks must maintain a due diligence process, conforming to RBI Guidelines on outsourcing of financial services, for the engagement of recovery agents. (iv) A repossession clause incorporated in a loan contract must be legally valid and must conform, in letter and in spirit, to the provisions of the Indian Contract Act, 1872. (v) Recovery agents engaged by banks and financial institutions must strictly adhere to the applicable Guidelines and instructions, including the Banking Codes and Standards Board of India (BCSBI) Code. (vi) Complaints received regarding violation of the Guidelines, or the adoption of abusive recovery practices, are to be viewed seriously by the RBI. (vii) The RBI may impose, and in cases of persistent breach extend, a ban upon a bank engaging recovery agents within a particular jurisdiction or function.
12
(viii) A repossession clause may contain: (a) the notice period before possession is taken; (b) the circumstances in which such notice may be waived; (c) the procedure for taking possession; (d) a final opportunity to the borrower to repay before sale or auction; (e) the procedure for restoring possession to the borrower; and (f) the procedure for sale or auction. (ix) Banks are encouraged to maintain a mechanism of credit counsellors to extend sympathetic consideration to deserving borrowers, and NBFC-Microfinance Institutions are required to display the Fair Practices Code, in the vernacular language, at their branch premises, with a corresponding declaration of accountability for staff conduct and grievance redressal incorporated into the loan agreement itself. (x) Recovery is ordinarily to be made at a central designated place; recourse to the borrower’s residence or place of work is permissible only where he fails to appear at the designated place on two or more occasions, and field staff must possess the minimum qualifications and training prescribed by the Fair Practices Code.
13
22. It is against this regulatory framework; relevant part of Article 11 of the Agreement needs to be examined which is extracted below for the facility of reference: “11. REPOSSESSION, TERMINATION AND COMPANY'S OTHER RIGHTS:
a) On the occurrence of any of the aforesaid Events Of Default contained in Article 10, the rights of the Borrower over the Asset shall stand determined void ipso facto without any notice and the Borrower shall be bound to deliver forthwith the Asset to the Company in the same condition in which it was originally received by him with all accessories/modifications done by Borrower whatsoever, ordinary wear and tear accepted and if the Asset is a vehicle, original Certificate of Registration with applicable Forms as prescribed in the statutes and/or rules made thereunder shall also be delivered to the Company along with the Asset. Failure or refusal of the Borrower to surrender the Asset shall constitute unlawful retention for which the Company shall be entitled to initiate legal action, without prejudice in other rights/legal remedies available to the Company.
i) Notice: In case of any default in repayment including an occurrence of any of the aforesaid Events of Default and/or failure to surrender the Asset as mentioned herein above, the Company shall cause a 7-day notice to be issued to the Borrower at his address as registered with the Company. The notice shall be deemed me to be served on the Borrower within 24 hours of posting, the notice by the Company even if the notice so served returns unserved for whatever reason and the confirmation from any authorized offer of the Company for having posted the notice to the Borrower shall be final and binding in this regard.
ii) Repossession: In case the Borrower fails to make payment of the dues or surrender the asset to the Company and/or rectify the breach of the terms of the contract in compliance with the notice mentioned
14
above, to the satisfaction of the Company, without prejudice to its other rights available under the Agreement, the Company may be entitled to take possession of the Asset (referred to as “repossession”) and for the said purpose, enter any place or places where the Asset may than be or is likely to be, remove or take possession of the same. The Borrower agrees and undertakes not to prevent or obstruct the Company from exercising its right of repossession of the Asset in the event of default by the Borrower. It shall be the sole responsibility of the Borrower to remove any goods (perishable, non-perishable) available in the Asset at the time of its repossession by the Company and the Borrower shall make his/their own arrangements to transfer such goods from the said Asset to and transport it back at his own cost and expenses and the Company shall not be liable to the Borrower for any damage, depreciation value, lose in transit etc. or for any damages arising on account of non-delivery of the same to anyone during or after such repossession.
iii) Post Repossession: Upon taking possession of the Asset, as a final chance to rectify the default, a 7 days notice that be caused by the Company to the Borrower to repay the termination price (which includes the charges and expenses incurred for taking possession of the Asset including the legal expenses). The notice shall be deemed to be served on the Borrower within 24 hours of posting the notice by the Company even if the notice is served returns unserved for whatever reason and the confirmation of any authorised officer of the Company for having posted the notice to the Borrower shall be final and binding in this regard.
iv) Waiver of Notice: The said notice (before and after taking possession of the Asset) mentioned here in above can be waived at the discretion of the Company, in case the Company is of opinion that such action is likely to jeopardize the Asset or the interest of the Company.
v) On payment of the termination price within the time and manner stipulated in the notice mentioned above,
15
the Company shall return the repossessed Asset to the Borrower or his authorized representative to be specified in writing by the Borrower. In case of failure on the part of the Borrower to make payment of the termination price within the time and manner stipulated in the notice mentioned above, the Company shall sell, dispose of the asset in the manner it may deem fit without any further notice to the Borrower notwithstanding exercising any other legal remedy or right against the Borrower available to it.
vi) The Borrower hereby irrevocably authorizes the Company to sell/transfer/assign the Asset without the Intervention of Court either by private treaty of public auction in such other manner as the Company may deem fit. The Borrower shall not be entitled to raise any objection regarding the regulatory of the sale and/or actions taken by the Company nor shall the Company be liable/responsible for any loss that may occasion by the exercise of such power and/or may arise from any act or default on the part of any broker or auctioneer or other person or body engaged by the Company for the said purpose.
vii) The Borrower shall forthwith deliver to the Company all original certificates and policies of insurance including Certificate of Registration (where the Asset is a vehicle), keys and all other documents relating to the Asset in the event of the failure of the Borrower to do so, the Company be entitled immediately apply to the concerned authorities and obtain the documents afresh, expenses for which shall be charged to the account of the Borrower and shall form part of the amount payable on the determination of this Agreement. The Borrower agrees and undertakes that he shall not raise any objection for such application by the Company.
viii) Upon sale of the Asset and adjustment of the said proceeds towards the Loan dues (which includes the expenses/charges incurred for parking, sale of Asset, in addition to the termination price), if there is any shortfall amount due and payable, the same shall be made good by the Borrower and/or the Guarantor. If
16
there is any surplus amount available after such adjustment, the Company shall, subject to the right of lien and Set-off against the Borrower and Guarantor, refund the balance, if any to the Borrower. b) Termination: On the surrender of the Asset by the Borrower or repossession thereof by the Company, notwithstanding the Term of Loan specified in the Schedule, the Agreement shall stand terminated without any notice. Without prejudice la the foregoing and/or any of the terms contained in this Agreement on termination, this Agreement may also stand terminated: i) by efflux of time an expiry of the Term of Loan specified in Agreement; or ii) earlier by a notice in writing from the Company to the Borrower and Guarantor, of is decision to do so. On such termination, the Company shall have like powers of repossession of the Asset as in a case where any Event of Default had occurred. On termination in any manner as above: iii) The Borrower and Guarantor shall not thereafter be entitled to the benefit: of payment by instalments of the amounts remaining payable which shall fall due immediately together with amount already in arrears, whether by way of instalments, additional interest or on any other account whatsoever. iv) The Borrower shall be liable to pay Additional Interest or the termination price at the rate mentioned in the Schedule, calculated from data of termination until realisation of the payment in full.
23. Thus, Article 11 in substance provides as follows: (i) On occurrence of an event of default as prescribed in Article 10, the rights of borrowers over the asset shall stand determined and the borrowers shall be bound to deliver forthwith the asset to the Company.
17
(ii) Failure or refusal of borrowers to surrender the asset shall constitute unlawful retention for which the Company shall be entitled to initiate legal action. (iii) In case of default in repayment including an occurrence of the event of the defaults or failure to surrender the asset, the Company shall cause a seven-day notice to be issued to the borrower at his address registered with the Company. (iv) In case, borrower fails to make payment of dues or surrender asset to the Company or to rectify the breach of terms of contract in compliance with the notice mentioned above, the Company may be entitled to take possession of the asset and for the said purpose may enter any place or places where the asset may then be or is likely to be, removed or take possession of the same. (v) Upon taking possession of the asset, as a final chance to rectify the default, a seven-day notice shall be sent by the Company to the borrower to repay the termination price, which includes charges and expenses incurred for taking possession of the asset including legal expenses. (vi) On payment of termination price within the time and manner indicated in the notice the Company shall return the
18
repossessed asset to the borrower or his authorized representative to be specified in the writing by the borrower. (vii) In case of failure on the part of the borrower to make the termination price within the time and manner stipulated in the notice, the Company shall sell, dispose of the asset in the manner it may deem fit, without any further notice to the borrower. (viii) The borrower irrevocably authorises the Company to sell/transfer/assign the asset without the intervention of the Court either by private treaty or public auction in such manner as the Company may deem fit. (ix) The borrower shall forthwith deliver to the Company, all original certificates and policy of insurance including certificates of registration where asset is a vehicle. (x) Upon sale of the asset and adjustment of the sale proceeds toward the dues, if there is any shortfall in the amount due and payable, the same shall be made good by the borrower and/or the guarantor. 24. Thus, Article 11 places the borrower entirely at the mercy of financier’s unilateral discretion, both as to whether notice will be given at all and as to the manner and timing of the sale. On a careful scrutiny of Article 11 of the Loan Agreement read with
19
Guidelines issued by the RBI, we are of the view that Article 11 is neither in consonance with the Guidelines issued by the RBI nor the provisions of the Indian Contract Act, 1872 for the reasons which follow. 25. Firstly, the stipulation that the borrower’s rights over the asset stand determined “ipso facto without any notice” upon the mere occurrence of an Event of Default is directly at variance with the requirement that a repossession clause must provide for a notice period before possession is taken. Secondly, the authorisation to recovery agents to “enter any place or places” in search of the asset is itself contrary to the RBI’s Guidelines and offends the requirement of a fair, lawful procedure for taking possession. Thirdly, the clause nowhere prescribes a procedure for taking possession or for sale and auction of the asset, leaving both wholly to the discretion of the Company. And fourthly, the power reserved to the Company to waive the notice altogether, at its own discretion, on its own assessment of jeopardy to its interest, converts what ought to be a floor of minimum protection into an illusory promise, defeasible at the will of the very party against whom it is meant to protect the borrower. A contractual term which permits one party unilaterally to dispense with the procedural safeguards designed to protect the other cannot be
20
regarded as being in conformity with either the RBI Guidelines or the general contractual requirement of fairness; to that extent, Article 11 does not meet the standard the law requires of a valid repossession clause. 26. Turning to the facts, the action taken against the appellant is shown to be in contravention both RBI Guidelines, which carry statutory force, and of the very terms of Article 11 on which the Company relies. No seven-day notice, as contemplated by Article 11(a)(i), was in fact issued to the appellant prior to repossession; the right of repossession, being conditional upon such notice, never accrued to the Company in the first place. The appellant’s specific and unrebutted case is that possession was taken at about 1:00 a.m. on 09.04.2023 by breaking open the steering lock of the vehicle, a mode of taking possession that is, by no stretch, peaceful, and one which bears every mark of the very ‘goonda- ism’ that this Court, in Prakash Kaur (supra), and the RBI, in its successive Guidelines, have condemned in unambiguous terms. The possession memorandum does not even bear the appellant’s signature which reinforces the conclusion that the vehicle was taken by the Company’s recovery agents without following the due process of law. The High Court failed to advert to this aspect
21
of the matter, which had a direct and material bearing on the controversy before it. 27. As regards the finding of the High Court that the writ petition was liable to be dismissed on the ground of delay, we find that this finding was arrived at without reference to the material on record. The appellant had lodged a First Information Report on the very day of the incident, 09.04.2023, and thereafter filed a complaint under Section 156(3) of the Code of Criminal Procedure, 1973 on 08.11.2023, in the bona fide belief that his vehicle had been stolen. He continued, moreover, to receive traffic challans on 18.01.2024, 18.11.2024 and 18.02.2025 in respect of a vehicle the Company claims to have sold as far back as 31.08.2023, a circumstance which, at the very least, called for explanation and ought to have weighed with the High Court. In these circumstances, we are unable to sustain the finding that the writ petition was liable to be thrown out on the ground of delay alone, without an examination of its merits and in the absence of any demonstrated prejudice to the Company. 28. Financial institutions, particularly those operating under the regulatory umbrella of the RBI, hold their repossession clauses on the implicit condition that they will be exercised within the four corners of the procedural safeguards, the RBI has, over two
22
decades, painstakingly, built, notice, an opportunity to cure, a fair mode of taking possession, and a transparent mode of sale. Where a financier steps outside that framework, breaks open a lock in the dead of night, takes possession without notice and without a signed memorandum, and thereafter treats the borrower merely as a source of residual liability, it forfeits the protection that the contract and the law would otherwise have afforded it, and exposes itself to the consequences in law of an unauthorised and arbitrary seizure. It is the balance discussed earlier in this judgment, between the legitimate need of the financier for an efficient recovery mechanism and the equally legitimate entitlement of the borrower to be treated fairly, with notice and due process, before he is deprived of the very asset by which he earns his bread, that the Company failed to observe on the facts before us. 29. For the foregoing reasons, impugned order dated 04.04.2025 passed by the High Court is quashed and set aside. The vehicle of the appellant has already been sold on 31.08.2023. Therefore, even though we do not approve of the unauthorised and arbitrary action of the Company in repossessing the vehicle and in selling the same, at this point of time, we are not inclined to set aside the sale.
23
30. The appellant is a man of modest means and was solely dependent on the vehicle for his livelihood by engaging it in the business of transportation. The appellant has been deprived of his right to livelihood in an arbitrary and an unfair manner. The impugned action of the Company constitutes a violation of Articles 14 and 21 of the Constitution. Therefore, the appellant is entitled to compensation. 31. The Guidelines/Master Circulars/Clarifications issued by RBI to NBFCs and Scheduled Commercial Banks have existed only on paper, and no steps have been taken by the RBI to implement it. We, therefore, direct the RBI to take effective steps to secure genuine compliance, by NBFCs and Scheduled Commercial Banks alike, with the Guidelines/Master Circulars /Clarifications, it has issued from time to time, so that incidents of the present kind, where a citizen is dispossessed of his livelihood in the dead of night, without notice and without recourse, do not recur. The Registry is directed to send a copy of this judgment to RBI. CONCLUSION 32. We, therefore, issue following directions: (i) The company shall close both the loan accounts of the appellant.
24
(ii) The Company shall refund the sum of Rs. 4,50,000/- (Rupees Four Lakh Fifty Thousand only) that is the sale price for which the vehicle of the appellant was sold. The said amount shall carry interest at the rate of 6% per annum from the date of sale till the payment is made to the appellant. (iii) The appellant is held entitled to a sum of Rs.10,00,000/- (Rupees Ten Lakhs only) as compensation in lieu of mental agony caused to him and loss of his livelihood for a considerable period. 33. In the result, the appeal is allowed with costs which are quantified at Rs. 50,000/- (Rupees Fifty Thousand only). 34. Pending applications, if any, shall stand disposed of.
……………..……………………………….J. [PAMIDIGHANTAM SRI NARASIMHA]
…….…………………………………………J.
[ALOK ARADHE]
NEW DELHI; SEPTEMBER 16, 2026.