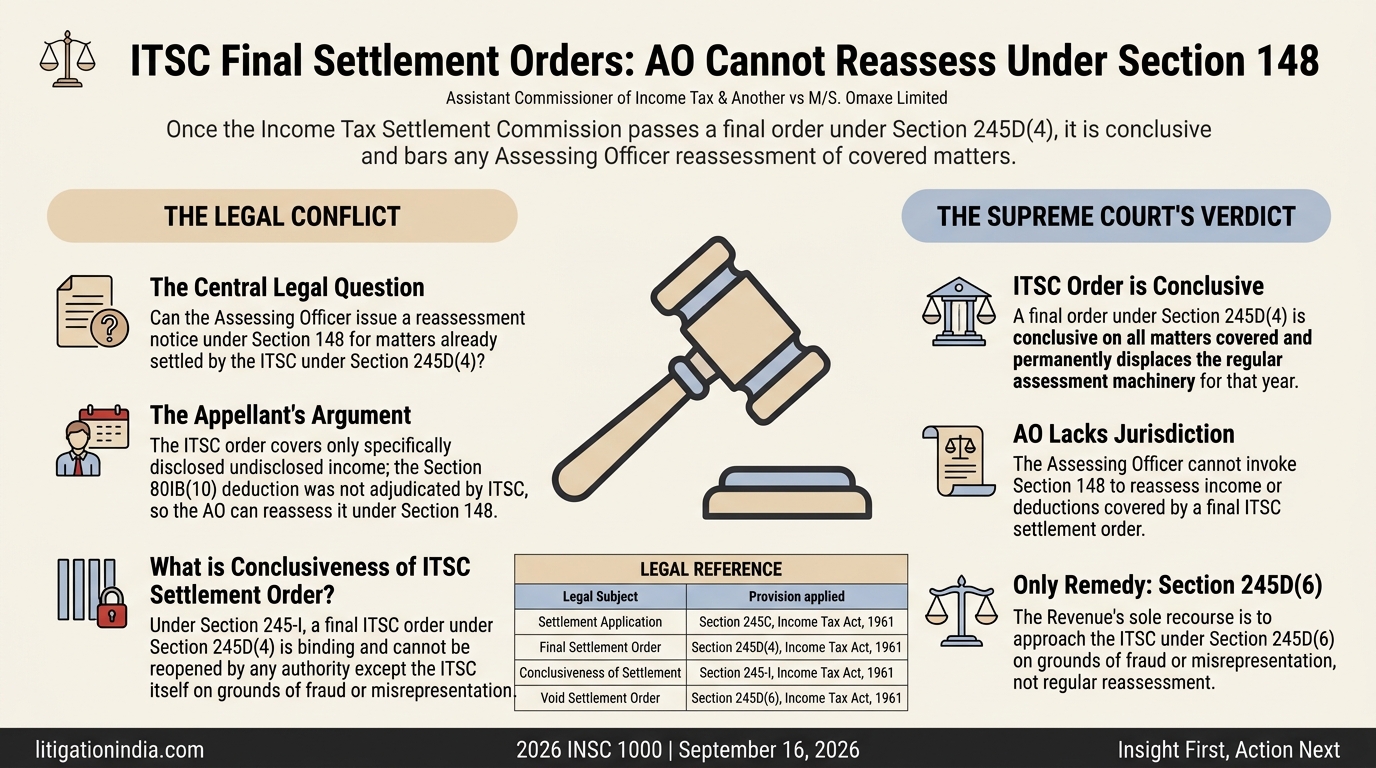
Full text of the judgment
Verbatim text extracted from the reported judgment in Assistant Commissioner of Income Tax & Another vs M/S. Omaxe Limited. For the authoritative version, refer to the Supreme Court of India's official website.
2026 INSC 1000
1
REPORTABLE
IN THE SUPREME COURT OF INDIA CIVIL APPELLATE JURISDICTION
CIVIL APPEAL NO. 9190 OF 2013
ASSISTANT COMMISSIONER OF INCOME TAX & ANOTHER
… APPELLANT(S)
VERSUS
M/S. OMAXE LIMITED
… RESPONDENT(S)
J U D G M E N T
S.V.N. BHATTI, J. 1. The Appellant is the Revenue. The Civil Appeal arises from the Judgment dated 13.07.2012 in Writ Petition (C) No. 7975 of 2011 in the High Court of Delhi. By the impugned Judgment, the High Court quashed the Show Cause Notice dated 30.06.2010, read with the Reassessment Order dated 08.11.2011, under Sections 148 and 147 read with Section 143(3) of the Income Tax Act, 1961 (“The Act, 1961”), under which the deduction claimed by the Assessee under Section 80IB(10) of the Act, 1961 was disallowed, resulting in an addition of Rs.65,65,17,999/- (Rupees Sixty-Five Crores Sixty- Five Lakhs Seventeen Thousand Nine Hundred and Ninety-Nine) to the total income of the Assessee/OMAXE Limited for the 2006-07 (Financial Year 2005-06). The circumstances preceding the impugned Judgment in the Writ Digitally signed by SNEHA DAS Date: 2026.09.16 17:45:14 IST Reason: Signature Not Verified
2
Petition are few, and, given the nature of the contentions urged on behalf of both the sides, they are referred to chronologically. 2. The Assessee is a Public Limited Company engaged in real estate and is under the jurisdiction of the First Appellant for assessment and the Second Appellant for the administrative charge, respectively. The Appeal relates to the Return filed on 30.11.2006 by the Assessee for the Assessment Year (AY) 2006-07. On 22.09.2005, the Revenue, under Section 132 of the Act, 1961, conducted a search and seizure at the Assessee’s business premises and the Associate Concerns, as well as the residential premises of its Directors. On 30.11.2006, the Assessee filed the Return for the AY 2006-07, declaring taxable income of Rs.89,20,76,630/- (Rupees Eighty Nine Crores Twenty Lakhs Seventy Six Thousand Six Hundred Thirty) and claimed a tax deduction of Rs. 78,99,00,509/- [noted as Rs.79,17,72,794/- in subsequent departmental proceedings] under Section 80IB(10) of the Act, 1961, in respect of the Housing Projects executed by the Assessee. On 31.05.2007, during the pendency of the regular assessment for the AY 2006-07, the Assessee filed an Application under Section 245C of the Act for the AY 2000-01 to 2006-07 to settle the cases as disclosed in the Application filed before the Income Tax Settlement Commission (“ITSC”). On 17.03.2008, the ITSC, under Section 245D(4) of the Act, 1961, passed the final Settlement Order. For AY 2006-07, the ITSC accepted the additional income surrender of Rs. 18,00,000/- (Rupees Eighteen Lakhs). The total income before deductions is Rs. 89,20,76,630/-, and after allowing deductions under Section 80IB(10) of the Act, 1961, the ITSC determined the net taxable income for the AY 2006-07 to
3
be Rs. 89,38,76,630/-. (Rupees Eighty-Nine Crores Thirty-Eight Lakhs Seventy-Six Thousand Six Hundred and Thirty). 3. According to the Revenue, on 17.12.2009 and 18.12.2009, the Investigating Wing of the Revenue conducted a fresh survey of the Assessee’s premises under Section 133A of the Act, 1961. According to the Revenue, the Assessee claimed a deduction under Section 80IB and, as part of an alleged manipulative process, was planning to transfer commercial portions of the projects executed on OMAXE City Lucknow, OMAXE City Sonepat, etc., to 100% subsidiary companies to maintain the commercial area, thereby enabling the Assessee to continue claiming the deduction under Section 80IB of the Act, 1961. On 30.06.2010, a Notice under Section 148 of the Act, 1961 was issued for the AY 2006-07, proposing to disallow the deduction under Section 80IB(10) of the Act, 1961 to the extent of Rs.55,58,96,486/- (Rupees Fifty-Five Crores Fifty-Eight Lakhs Ninety-Six Thousand Four Hundred Eighty-Six). The reasons recorded by the Assessing Officer (“AO”) for issuing the Notice under Section 148 are as follows: A. A survey was conducted under Section 133A on 17.12.2009 and 18.12.2009 at the Assessee’s premises. During the survey, the Investigation Wing impounded documents containing Minutes of a Meeting attended by Senior Executives, including the Director of Taxation, the V.P. Finance, the G.M. Legal, and the Company’s Auditors. B. The impounded documents show that the Assessee's Executives mutually decided, before finalising the balance sheet for the period ending 31.03.2009, to transfer the commercial portions of specific projects to 100%
4
subsidiary companies at cost to strengthen their claim under Section 80IB of the Act, 1961. C. Section 80IB(10)(vi) of the Act, 1961 provides that the built-up area of shops and other commercial units within a housing project must not exceed 5% of the aggregate built-up area or 2,000 sq. ft., whichever is lower. D. Further, the impounded documents showed that the commercial area in several of the Assessee's projects far exceeded the legal limit, making those projects ineligible for the deduction under Section 80IB(10)(vi) of the Act, 1961. Therefore, the Section 80IB deductions were wrongly claimed. E. Hence, Rs. 55,58,96,486/- across four specific projects, i.e., OMAXE City Lucknow, OMAXE City Sonepat, OMAXE Heights Sonepat, and OMAXE Heights Faridabad, had escaped assessment, and these reasons were sufficient to issue a Notice under Section 148 of the Act, 1961, for AY 2006- 07. 4. In response, the Assessee filed objections on 20.09.2010 and 18.08.2011 against the proposed reopening of the ITSC Settlement Order dated 17.03.2008 for AY 2006-07. On 18.07.2011, the AO/First Appellant issued a Notice under Section 143(2) of the Act, 1961, seeking further details from the Assessee. In response to the said Notice, the Assessee filed Preliminary Objections, contending that the ITSC Settlement Order was conclusive under Section 245I and that the AO had no jurisdiction to reopen the assessment. The reply stated as follows:
5
A. That the Assessee has filed an application before the Settlement Commission for the determination of total income derived under the Act, 1961, and for the settlement of tax liabilities for AY 2006-07. The ITSC passed an Order under Section 245D(4) of the Act, 1961, computing the total income for AY 2006–07. Consequently, all matters relating to AY 2006–07 are settled and conclusive. B. Section 245-I of the Act, 1961, mandates that every Order of settlement passed under Section 245D(4) is conclusive on the matters stated therein. The said Section strictly bars the reopening of any matter covered by such an Order in any proceeding under the Act, 1961 or any other law in force, except as otherwise provided under Chapter XIX-A of the Act, 1961. C. On a plain reading of Section 245-I, the AO lacks statutory jurisdiction under the Act, 1961, to issue a Reassessment Notice under Section 148 for the subject assessment year. Accordingly, the Notice dated 30.06.2010 is illegal, void ab initio, and bad in law. D. The AO is requested to drop the proceedings initiated under Section 148 of the Act, 1961. In the event the proceedings are not dropped immediately, the Assessee requests the AO to supply a copy of the “reasons recorded” for issuing the Section 148 notice for AY 2006–07. 5. The AO, vide Order dated 03.10.2011, rejected the Assessee's objections to the Notice dated 30.06.2010, which ultimately led to the reassessment Order dated 08.11.2011 under Section 147 of the Act, 1961. The AO disallowed the deduction under Section 80IB(10) and added back Rs.65,65,17,999/- (Rupees Sixty-Five Crores Sixty-Five Lakhs Seventeen
6
Thousand Nine Hundred and Ninety-Nine) to the total taxable income for AY 2006-07. 6. On 04.01.2012, at the first instance, the Assessee filed Writ Petition No. 7975 of 2011 before the High Court of Delhi, challenging the Show Cause Notice dated 30.06.2010. The prayer was subsequently amended on 09.01.2012 to challenge the Reassessment Order dated 08.11.2011. 7. The following table sets out the disclosure of income and the deduction claimed by the Assessee for the AY 2006-07 in the return and the disclosure application: Income Tax Returns dated 30.11.2006
Gross Total Income 1683849122
Less: Deductions (Chapter VI-A) u/s 80 G Donation
Eligible for 50% 3743970 1871985
Eligible Deduction U/S 80IB 789900509 791772494
Total Income 892076628 Round off u/s 288A 892076630
Revised Computation of Income and Tax in Application u/s 245C(1) of the Act
Income originally returned 892,076,630
Additional income surrendered 1,800,000 893,876,630 Tax Due 268,162,989 Add: - S/c @10% 26,816,299 294,979,288 Add: - Education Cess @ 2% 5,899,586 300,878,874 Less:- Tax Paid 300,272,994 605,880
8. It is a matter of record that on 29.10.2010, the CIT(C)-III, Delhi, filed an Application under Section 245D(6) of the Act, 1961, before the ITSC, seeking to declare that the Order dated 17.03.2008 in favour of the Assessee under Section 245D(4) is on account of misrepresentation of facts and is void
7
under Section 245D(6) of the Act, 1961. After receiving the Assessee's reply, the ITSC afforded the Revenue and the Assessee an opportunity of hearing on 30.11.2011 and, by Order dated 16.12.2011, rejected the Revenue's Application dated 29.10.2010. The Order dated 16.12.2011, in sufficient detail, addressed the assumption of jurisdiction and the invocation of Section 148 of the Act, 1961, proposing to re-assess the AY 2006-07. It noted the distinction drawn by the Revenue that the ITSC Order dated 17.03.2008 is confined to the income disclosed under Section 245C and that no other matters covered by the regular assessment were considered by ITSC, and hence rejected the Application. 9. To complete the narrative chronologically, we also excerpt verbatim the Order dated 16.12.2011 of the ITSC under Section 245D(6) of the Act, 1961, to explain that the ground on which reassessment was initiated did not find favour with the ITSC: “The CIT(C)-III, Delhi, vide application dated 29.10.2010, in this case has requested that in view of the applicant claiming wrong deduction for its various projects under section 80IB(10) of the Income Tax Act had obtained the settlement order under section 245D(4) dated 17.03.2008 by misrepresentation of facts and accordingly the same be declared void as per provisions of section 245D(6). xxx
xxx
xxx 5. According to the CIT, from the material impounded during the survey, it can clearly be seen that the claim of deduction under section 80IB(10) is not available on some of the projects because the commercial area of these projects is much more than the limits specified in section 80IB(10)(vi) of the Act i.e. 5% of the aggregating built up area of the Housing Projects or 2000 Sq.feet whichever is less. ……….:- 6. Thus, according to the CIT, deduction under section 80IB in respect of the above projects has wrongly been claimed by the applicant. As commercial area in these projects was more than limit prescribed in the Act, these projects were not eligible for deduction under section 80IB(10). As per the CIT, deduction of Rs.55,58,96,486/- claimed by the applicant has to be disallowed in A.Y. 2006-
8
07. The CIT goes on to state: “In fact, the assessee had willfully concealed this fact before the Settlement Commission while moving its application for settlement. Thus, the assessee has not made full and true disclosure of its income, which is a pre-requisite condition for settlement as provided under section 245C. xxx
xxx
xxx 23. We have carefully gone through the material on record and the rival submissions. We find that the main reason given by the CIT for moving the application under section 245D(6) is the evidence found during the course of survey under section 133(A) dated 17/18.12.2009 (para-3 of the CIT’s letter dated 18.02.2011). A perusal of this evidence nowhere makes out any case of misrepresentation by the applicant. Minutes of the meeting of records in the CIT’s application dated 29.10.2010 only talks of strengthening the claim of deduction under section 80IB(10). There is no hint in the minutes of stating wrong facts or suppressing material facts by the applicant. In fact, in the communication quoted in para- 6.3 of the Assessing Officer’s letter dated 04.02.2011, the applicant’s desire to strictly comply with the requirements of law and complete the projects within the stipulated time is clearly demonstrated. 24. The difference of opinion between the Department and the applicant on the issue of what constitutes a ‘project’ liable to deduction under section 801B(10) is a legal dispute and can by no stretch of imagination be said to be misrepresentation on part of the applicant. The applicant is fully entitled to hold and agitate his point of view as provided under law. 25. Although the applicant has been persisting with the stand that the issue stands covered by the Commission’s order, we find that the A.O. had issued notice under section 148 in this case of A.Y. 2006-07 on the premise that the issue of deduction was not covered by the order u/s. 245D(4). He thereafter, also proceeded to complete assessment under section 144 during the pendency of application under section 245D(6) before the Commission. The stand of the CIT is contradictory; on one hand he is holding that the issue of deduction under section 80IB(10) was not covered by the impugned order under section 245D(4), while on the other hand alleging misrepresentation on the issue by the applicant before the Settlement Commission. We are unable to appreciate how can there be misrepresentation on an issue not considered and covered in the order of the Settlement Commission. xxx
xxx
xxx 27. For the reasons summed up in the preceding paragraphs, the application of the CIT filed under section 24D(6) to declare the order passed under section 245D(4) dated 17.03.2008 as void is held to be devoid of merit, misconceived and non-maintainable, the same is accordingly rejected.”
9
10. In Writ Petition (C) No. 7975 of 2011, the objections raised by the Assessee are summarised as under: A. The AO is attempting to usurp the exclusive jurisdiction vested solely in the Settlement Commission. The AO’s actions are entirely contrary to the letter and spirit of Chapter XIX-A of the Act, 1961. B. The AO failed to appreciate that the matter before the Settlement Commission for the year under consideration was a regular income assessment. C. Once the ITSC passes a final Order of Settlement under Section 245D(4) of the Act, 1961, the assessment attains finality and becomes conclusive. Consequently, the AO has no jurisdiction to reopen any matter relating to that assessment year by issuing a Notice under Section 148 of the Act, 1961. D. Under Section 245-I of the Act, 1961, an ITSC Order is conclusive on the matters stated therein, and no matter can be reopened in any other proceeding. Hence, the Reassessment Order passed by the AO was wholly without jurisdiction and illegal. 11. The Revenue contested the writ prayer and, in fact, set out its plea on the income disclosed for settlement in the Application under Section 245C of the Act, 1961, and on matters not specifically covered by fresh disclosure under the said Section. The Revenue's objections before the High Court are as follows: A. That the ITSC's Order is conclusive only in relation to the specific matters and issues stated in the Settlement Order itself. The Assessee did not
10
specifically approach the ITSC to settle its claim for deduction under Section 80IB (10) of the Act, 1961. B. Furthermore, the Assessee did not disclose any income in respect of the housing project deduction. Therefore, ITSC did not adjudicate this specific claim, meaning the deduction claimed was not covered by ITSC's Order. C. Relying on Section 245F(4), it was contended that no finality attached to any matter not brought before the ITSC. As a result, there was no legal bar to the AO initiating reassessment proceedings in respect of the deduction under Section 80IB (10). D. The Revenue relied on the Supreme Court judgment in CIT v. Damani Brothers1 to contend that the ITSC lacks authority to address disclosed income and to decide whether to proceed with the Assessee's Petition. 12. By the impugned Judgment, the Writ Petition was allowed, quashing the Reassessment Notice and Order. It was held that the ITSC has exclusive jurisdiction once an Application for Settlement is admitted, and that its final Order legally bars the AO from initiating reassessment in respect of the impugned Order passed by the ITSC. The findings of the High Court are as follows: A. On Section 80IB(10) Deduction: The Revenue argued that the ITSC never formally adjudicated the Section 80IB(10) deduction because the Assessee did not disclose it as part of its undisclosed income. The ITSC rejected this, noting that the Assessee claimed a deduction of
1 (2003) 259 ITR 475.
11
Rs. 78,99,00,509/- in its original Return, resulting in an initially declared net taxable income of Rs. 89,20,76,630/-. The ITSC computed the final total income at Rs. 89,38,76,630/-, reflecting the deduction claimed in the original Return, thereby showing that the final Settlement Order covered the deduction. B. On the jurisdiction of Re-Assessment: i. The High Court relied on the Bombay High Court's Judgment in Major Metals Ltd.2 to affirm that Parliament intended the entire assessment process to rest exclusively with the Settlement Commission (ITSC). The Bombay High Court held that once the ITSC is seized of a proceeding, the law does not contemplate any parallel assessment. The ITSC's function is characterised by comprehensiveness and finality, so an AO cannot reopen an assessment the Commission has already finalised. ii. The view of the Allahabad High Court in Smt. Diksha Singh3 is endorsed, holding that the Parliament empowered the ITSC alone to deal with situations such as fraud or misrepresentation. Piecemeal determination of an assessee’s income, with part decided by the ITSC and the other by the AO, is legally impermissible and frustrates the fundamental purpose of settlement. iii. The High Court distinguished the Supreme Court's Judgment in Damani Brothers (supra), clarifying that it applied only to the preliminary stage, before the ITSC officially decides to proceed with a
2 W.P. No. 397 of 2011. 3 CIT v. Smt. Diksha Singh, [2013] 350 ITR 157 (All).
12
Settlement Application under Section 245D(1). Once the Application is admitted, the ITSC assumes full jurisdiction over both disclosed and undisclosed income, thereby rendering the Revenue's reliance on this Judgment invalid after the final Settlement Order is passed. The Damani Brothers (supra) clarified earlier observations in Express Newspapers Ltd.4 regarding the ITSC's role during the pendency of an Application under Chapter XIX-A of the Act, 1961. iv. Hence, the Statute does not, in principle, permit two divergent orders from different tax authorities to determine the total income for the same assessment year, as this would cause chaos in tax administration. C. On Statutory Interpretation: Under Section 245F(2) of the Act, 1961, the ITSC assumes exclusive jurisdiction to exercise the powers and perform the functions of an Income-Tax Authority the moment a Settlement Application is allowed to proceed. This exclusive jurisdiction continues until the ITSC passes the final Settlement Order under Section 245D(4) of the Act, 1961. Consequently, under Section 245-I, the ITSC's final settlement is strictly conclusive and can be reopened only if the ITSC itself discovers that the Order was obtained through fraud or misrepresentation. In Brij Lal and Ors. v. CIT,5 it was held that Chapter XIX-A of the Act, 1961, is a self- contained code. Accordingly, Section 147 of the Act, 1961, which governs reassessment by the AO, does not apply to the statutory scheme governing final ITSC settlements.
4 Commissioner of Income Tax, madras v. Express Newspapers Ltd., (1994) 2 SCC 374. 5 (2011) 1 SCC 1.
13
13. Hence, the Civil Appeal is at the instance of the Revenue. 14. We have heard learned Senior Counsel Mr. Arijit Prasad and Ms. Kavita Jha for the parties and have perused the record. 15. For the Revenue, it is argued that Chapter XIX-A of the Act, 1961, particularly Section 245C read with Section 245D, provides for the full and true disclosure of the Assessee’s income that had not been disclosed before the AO, and for payment of tax, penalty, and interest as may be decided by the ITSC. For the assessment year, the Assessee, in his Application, has, through the revised computation, disclosed the tax payable on the disclosed income under Section 245C, amounting to Rs. 6,05,880/- (Rupees Six Lakhs Five Thousand Eight Hundred Eighty). The Notice under Section 148 of the Act, 1961 does not sit in appeal or reopen an issue concluded by the ITSC vide Order dated 17.03.2008. The Assessee is not entitled to claim a deduction under Section 80IB(10) of the Act, 1961. This aspect was not considered in the Order dated 17.03.2008. Therefore, the Show Cause Notice dated 30.06.2010 under Section 148 neither reopens an aspect concluded by the Order of the ITSC nor reopens an Order which has attained finality under Section 245D(4) of the Act, 1961. The issue of reassessment under Section 148 arose on account of further search and seizure by the Revenue on 17.12.2009 and 18.12.2009. The filing of the Application under Section 245D(6) and the Order dated 16.12.2011 reinforce the stand of the Revenue. The learned Senior Counsel argues that, by a catena of decisions of this Court, the scope and object of Chapter XIX-A of the Act, 1961, is no longer res integra, and the Revenue is proposing to reassess income escaped and to levy
14
taxes on account of claiming an inapplicable deduction under Section 80IB(10) of the Act, 1961. 16. Per contra, Ms. Kavita Jha contends that the Revenue is applying Section 245C of the Act, 1961 incorrectly and incompletely. The Assessee, desirous of settlement under Chapter XIX-A of the Act, 1961, makes an Application in the prescribed Form No. 34B. The Assessee has computed the net taxable income after claiming permissible statutory deductions under Section 80IB of the Act, 1961, and has offered additional tax after accounting for the additional undisclosed income and finally deriving the income on which the tax is payable. The ITSC admitted the Application. The ITSC sought a reply to the Application filed by the Assessee and, after hearing the representatives of the Assessee and the Principal Commissioner, Income Tax, passed the Order dated 17.03.2008. The attention of the Court is invited to the procedure followed by the Assessee for claiming deduction under Section 80IB(10) of the Act, 1961. It cannot be gainsaid that the Revenue and the ITSC have considered the net income liable for tax without appreciating the deductions claimed by the Assessee. It is argued that if the Assessee is not entitled to any deductions, including the recent eligible disclosure by the AO, the Revenue ought to have filed objections on this behalf as well. The Settlement Orders were passed on the basis of the record, including the scheme of deduction under Section 80IB(10) of the Act, 1961. The Orders, in terms of Section 245D of the Act, 1961, attained finality vis-à-vis the Revenue and the Assessee. The AO is not vested with the power to reopen matters considered and ordered by the ITSC.
15
16.1 It is further contended that, without admitting that the Assessee resorted to misrepresentation, suppression or fraud while pursuing the remedy under Chapter XIX-A of the Act, 1961, the legal course of action available to the Revenue is to move the ITSC under Section 245D(6) of the Act, 1961. The Revenue has availed of this remedy as well, and by Order dated 16.12.2011, the ITSC rejected the Application. Therefore, the AO is denuded of any power to reopen matters concluded and reaffirmed by the ITSC. For the Assessee, the following citations are relied upon: i. Jyotendrasinhji v. S.I. Tripathi & Ors. (1993) Supp (3) SCC 389; ii. CIT, Madras v. Express Newspaper Ltd. (supra) iii. Brij Lal & Ors. v. CIT, Jalandhar (supra); and iv. Kotak Mahindra Bank Ltd. v. CIT & Anr. (2023) 458 ITR 113 (SC).
17. We refer to the precedents before considering the question at hand. In Jyotendrasinhji v. S.I. Tripathi (supra), this Court considered the scope of judicial review of the Settlement Commission’s Orders. The assessee challenged the ITSC Order on the assessability of income derived from five foreign trusts established by the assessee’s father. This Court examined whether the United States Trusts were revocable transfers under Section 63 of the Act, 1961, and whether the Revenue could tax beneficiaries directly on income “received” from discretionary Trusts; and upheld the Settlement Commission's decision to tax Trust income in the settlor’s hands during his lifetime and thereafter in the beneficiary-assessee’s hands, emphasising the limited scope of judicial review under Article 136 of the Constitution of India
16
against the Settlement Commission's Order. The observations on the scope of judicial review against the Settlement Commission Orders are as follows: A. The finality clause in Section 245-I of the Act, 1961 does not, and cannot, bar the High Court's constitutional jurisdiction under Article 226 of the Constitution of India or the Supreme Court's under Articles 32/136 of the Constitution of India. B. The scope of judicial review of the Settlement Commission is strictly limited to examining whether the Commission's Order is contrary to any provision of the Act, 1961, and whether any such contravention has prejudiced the assessee. C. Interference by the Court is also permissible on independent grounds of bias, fraud, or malice. D. In this context, judicial review under Article 136 concerns the decision- making process, not the merits of the ITSC’s Settlement Order. E. An incorrect interpretation of a Settlement or Trust Deed by the Commission does not violate the provisions of the Act, 1961, and therefore cannot be a valid ground for interference.
18. In CIT, Madras v. Express Newspapers Limited (supra), this Court examined the maintainability of an application to the ITSC under Section 245C of the Act, 1961. It clarified that an Application must disclose previously undisclosed income and cannot be used to forestall ongoing investigations where the Tax Authorities have already established, or are likely to establish, concealment or fraud. Further, the ITSC can consider investigative material
17
the Authorities collect after the Settlement Application is filed. The observations are summarised as follows: A. On Nature of Disclosure under Section 245C: An Application under Section 245C is maintainable only if it discloses income that has not previously been disclosed to the AO. The Assessee's disclosure must be a voluntary disclosure of concealed income. The Application must also disclose how the undisclosed income was derived. An Application that merely offsets a portion of the claimed losses against taxable income, without disclosing any new income or the manner of its derivation, does not fulfil the requirements of Section 245C(1) of the Act, 1961, and must be rejected in limine. B. On Scope of Settlement Commission’s Jurisdiction: Once the Commission admits an Application under Section 245C for consideration, it withdraws the case from the relevant Assessing, Appellate, or Revising Authority. The proceedings before the Settlement Commission are not confined solely to the income disclosed in the Application. The Commission transfers the entire case for that assessment year and deals with it exclusively. C. On Bar on Forestalling Tax Investigations: The purpose of Chapter XIX- A of the Act, 1961 is not to accommodate assessees who approach the Commission only after the discovery of their concealed income or of fraud they have perpetrated. If the Income Tax Authorities have already discovered the undisclosed income, or are at a stage of investigation where the gathered material is likely to establish the particulars of such income or fraud, the assessee cannot use the Settlement Commission to defeat or forestall the
18
investigation. An assessee should not be permitted to take advantage of the comparatively easier course of settlement to avoid normal assessment channels if the Department already possesses material that establishes, or is likely to establish, concealment or fraud. D. On Admissibility of Evidence after the filing of the Application: The Settlement Commission cannot lawfully refuse to consider material collected by the Commissioner after the date the Application was filed under Section 245C of the Act, 1961. Filing a settlement Application is a unilateral act, and the Income Tax Authorities may continue their investigations and rely on evidence collected up to the date they submit their report to the Commission. The proper timeline for considering evidence is ordinarily based on the date the Commissioner submits the Report, not the date the Assessee files the Application. The Commission may also review material collected by the Income Tax Authorities even after the Commissioner submits the Report if it believes the interests of justice require it. 19. In Brij Lal (supra), the Constitution Bench examined the scheme and framework of Chapter XIX-A, the procedure before the Settlement Commission, and the binding nature of the Commission's Orders. It clarified the application of Sections 234A, 234B, and 234C of the Act, 1961, to proceedings before the Settlement Commission under Chapter XIX-A. It held that interest for default in payment of advance tax under Section 234B of the Act, 1961, is chargeable only up to the admission of the Settlement Application under Section 245D(1), not up to the final Order under Section 245D(4). It further held that the Settlement Commission lacks jurisdiction to
19
reopen concluded proceedings under Section 154 to levy such interest. The observations are summarised as follows: A. The special procedure under Chapter XIX-A of the Act, 1961 for settling cases contains an in-built mechanism for computing total income, which forms the basis of the assessment. Therefore, the provisions for levying interest for default in payment of advance tax, specifically Sections 234A, 234B, and 234C of the Act, 1961, are applicable to proceedings before the Settlement Commission up to the stage of the Order passed under Section 245D(1) of the Act, 1961. B. The terminal point for charging interest under Section 234B of the Act, 1961, is the date of the Order under Section 245D(1), i.e., the stage at which the Settlement Commission admits the case for further proceedings. The liability to pay interest does not extend to the date of the final Settlement Order under Section 245D(4). Parliament did not contemplate levying interest between the admission stage and the ITSC’s final disposal. C. The Settlement Commission lacks authority to invoke Section 154 of the Act, 1961, which provides for rectification of mistakes apparent from the record, to reopen its concluded proceedings for levying interest under Section 234B. Under Section 245-I, orders passed by the Settlement Commission are final and conclusive and can be reopened only in specific instances of fraud or misrepresentation. Unlike the Income Tax Appellate Tribunal (ITAT), the Settlement Commission has not been conferred with statutory powers of rectification.
20
D. The procedure for settlement under Chapter XIX-A is a self-contained code, akin to arbitration proceedings. The objective of this Chapter is the “settlement of liability” rather than the “determination of liability”. Consequently, an Order passed by the Settlement Commission under Section 245D(4) is distinct in nature and not equivalent to an Order of regular Assessment under Sections 143(1), 143(3), or 144 of the Act, 1961. E. The AO’s jurisdiction is not automatically fettered the moment an assessee files a Settlement Application. The Settlement Commission assumes exclusive jurisdiction to exercise the powers of an Income Tax Authority only after it passes an Order under Section 245D(1) permitting the Application to proceed. 20. In Kotak Mahindra Bank Limited (supra), the issue was whether the High Court correctly interfered with a Settlement Commission Order granting an Assessee immunity from prosecution and penalty under Section 245H of the Act, 1961. This Court held that the High Court erred in remanding the matter, as the Commission had properly based its decision on the assessee's full and true disclosure and cooperation during the proceedings. It further held that judicial review of the Settlement Commission’s discretionary orders is strictly limited. Accordingly, the Court restored the assessee's immunity under the Settlement Order. The Court held as follows: A. For the Settlement Commission to grant immunity from prosecution and penalty under Section 245H(1) of the Act, 1961, two essential conditions must be met:
21
1. The Assessee must have made a full and true disclosure of its income and the manner in which it was derived; and 2. The Assessee must have co-operated with the Settlement Commission during the proceedings. B. The material “disclosed” by an Assessee before the Settlement Commission need not be entirely distinct from what was previously “discovered” by the AO. An Assessee may accept the liability, wholly or partly, as determined by the AO and subsequently approach the Commission to offer additional income to tax, which still qualifies as a “full and true disclosure”. C. The power vested in the Settlement Commission under Section 245H is discretionary. In exercising this discretion, the Commission is bound to consider the following specific relevant materials: 1. The Report submitted by the Commissioner under Section 245D(1). 2. The disclosures made by the applicant regarding the income and its source. 3. Any other relevant evidence introduced by the Assessee or by the Department. D. No single formula applies universally to every case regarding the grant of immunity from prosecution under the Act, 1961. The Commission must decide each case on its specific facts and circumstances, provided the pre- conditions, i.e., disclosure and cooperation, are met. E. High Courts and the Supreme Court have a limited scope for judicial review of the Settlement Commission’s discretionary orders. Courts must not act as appellate bodies to scrutinise or weigh the sufficiency of the material
22
and particulars placed before the Commission. Interference is strictly limited to instances where the Commission's Order contravenes the provisions of the Act, 1961; prejudices the opposite party; or is vitiated by fraud, bias, or malice. 21. The precedents on the point make a few issues canvassed in the Civil Appeal fairly settled. The precedents may not be closer to the circumstances considered by this Court in this Appeal. In one sense, the circumstances are more solid and favourable to the Assessee, and in another, independent sense, the precedents referred to above provided useful guidance to this Court in appreciating the challenge to the Reassessment Notice under Section 148 of the Act, 1961. The question is whether, notwithstanding an Order under Section 245D(4) of the Act, 1961, the AO has jurisdiction under Section 148 of the Act, 1961, to propose reassessment of an aspect covered by the Settlement Order. The Judgment of this Court in Brij Lal (supra) considered whether the Settlement Commission can reopen its concluded proceedings by recourse to Section 154 of the Act, 1961, to levy interest under Section 234B of the Act, 1961, if it was not done in the original proceedings. The answer is that invocation of Section 154 of the Act by the Settlement Commission cannot be justified. The precedent is to the effect that even the scope of re- opening by the ITSC is not complete or referable to any other Section in the Act, 1961, except through Chapter XIX-A of the Act, 1961. The circumstances and the reasons for incorporating Chapter XIX-A of the Act, 1961, are considered in the precedents noted supra. The facility of resolution through Chapter XIX-A can be said to be summed up as a purification of accounts
23
from distorted, suppressed and misrepresented entries of income and expenditure by an Assessee. This is not a simple holy shower but an opportunity to purge by paying the tax, penalty, and interest as may be determined by the ITSC. The procedure under Chapter XIX-A of the Act, 1961, is optional and enables voluntary disclosure by the Assessee for the final determination of tax payable for disputes before the ITSC. Once the Assessee makes an Application, the Assessee cannot withdraw it. 22. Per contra, the Revenue is afforded an opportunity to file a Report, place material before the ITSC, and request that the ITSC reject the Application under Section 245C of the Act, 1961, and allow the regular procedure for finalisation of the assessment to be undertaken in accordance with the Act, 1961. Let us briefly summarise the roadmap under Chapter XIX-A of the Act, 1961: A. The statutory settlement framework under Chapter XIX-A of the Income Tax Act, 1961, serves as a specialised alternate dispute resolution mechanism that directly intersects with and temporarily overrides the regular assessment machinery under Sections 142 to 156 of the Act, 1961. B. The settlement procedure cannot be invoked in a vacuum. It requires an active, pending proceeding under the regular assessment machinery as a statutory precondition, namely: i. An assessment, reassessment, or search assessment proceeding must be pending against the taxpayer under Sections 142-144 (inquiry and assessment), Sections 147–148 (income escaping assessment/reopening), or Sections 153A–153C (search and requisition
24
assessments) of the Act, 1961. Without a pending proceeding, the ITSC lacks jurisdiction to entertain an Application. ii. The Assessee must have already filed the required Income Tax Return for the assessment year(s) in question before making the Settlement Application. iii. The additional income tax payable on the undisclosed income disclosed in the Settlement Application must exceed the statutory minimum threshold of Rupees Ten Lakhs. iv. The Application must be filed in the prescribed official form and must contain a full and true disclosure of the undisclosed income, the specific manner in which such income was derived, and the detailed computation of additional tax due. (emphasis added)
v. The Application must be accompanied by the statutory fee prescribed under the Rules. vi. Once an Application under Section 245C is submitted, it is irrevocable and cannot be withdrawn by the applicant under any circumstances. C. Exclusive Jurisdiction: Upon submission, the ITSC or the Interim Board processes the Application. This stage marks a fork in the road between ordinary assessment and the settlement route. i. Within 7 days of receiving the Application, the Authority issues a Notice to the Applicant, requiring an explanation as to why the Application should be allowed to proceed.
25
ii. Within 14 days of receipt of the Application, the Authority must pass a written Order either rejecting the Application or allowing it to proceed. If no Order is passed within this period, the Application is deemed to be allowed to proceed. iii. If the Application is not allowed to proceed, the regular assessment machinery remains undisturbed, no exclusive jurisdiction vests in the ITSC, and the AO continues proceedings under Sections 142 to 156 of the Act, 1961, as before. iv. If the Application is admitted (or deemed admitted), Section 245F(2) is triggered immediately. The ITSC assumes exclusive jurisdiction over the case. Because two Authorities cannot simultaneously exercise jurisdiction over the same subject matter, the regular assessment machinery, i.e., Sections 142–156, including inquiry, reassessment, search assessments, rectification, and demands, is placed in statutory abeyance. D. Once admitted, the case proceeds towards settlement of the income tax payable on the Application filed by the Assessee and other amounts payable thereon. The ITSC then calls for a comprehensive report from the Principal Commissioner or the Commissioner of Income Tax, which must be submitted within 45 days. The ITSC then reviews the Commissioner's Report, the underlying records, and the case’s complexity. Both the Applicant and the Commissioner are given an opportunity to be heard, and the ITSC may direct further inquiries or investigations, if warranted.
26
E. Proceedings under Section 245D of the Act, 1961, conclude in one of two ways: i. The ITSC passes a conclusive Order settling the terms, including the determination of total income, tax liability, interest, and penalty. The order attains finality and permanently displaces the regular assessment machinery under Sections 142 to 156 for the subject assessment years. Any tax or liability determined must be paid within 35 days of receipt of the Order. Delayed payments attract simple interest at 15% per annum. ii. If the Application abates under Section 245HA, the freeze under Section 245F(2) is lifted. The AO’s jurisdiction revives, and regular assessment or reassessment proceedings resume from the stage at which they were placed in abeyance. The proceedings do not restart from zero; all confidential disclosures, submissions, and materials placed before the Commission remain fully available and admissible for the AO’s use. F. To ensure the Revenue is not prejudiced during the interlude before the ITSC, the statutory limitation period under Sections 153 and 153B is protected. The entire period from the date the Settlement Application is filed until the date it is rejected, disposed of, or abated is excluded from the time limits for completing assessments. If the AO abates the matter under Section 245HA, the law extends or carves out this period, thereby giving the AO the full statutory runway to complete the revived assessment proceedings. G. Section 245H also empowers the ITSC to grant immunity from prosecution for offences under the Income Tax Act or the Indian Penal Code,
27
as well as partial or total immunity from penalties, provided the applicant has cooperated and made a full and true disclosure. H. Under Section 245-I, Orders passed under Section 245D(4) are conclusive on the matters stated therein. No appeal lies against an ITSC Order. It can be challenged only under the extraordinary writ jurisdiction of the High Courts (Article 226) or the Supreme Court (Articles 32/136) on limited grounds, such as procedural violations, lack of jurisdiction, or violation of natural justice. I. A Settlement Order obtained by fraud or misrepresentation of facts is void under Section 245D(6), enabling the regular assessment machinery to reopen and assess the escaped income without any limitation. 23. The Revenue’s argument for issuing the Reassessment Notice rests on the words in Section 245C of the Act, 1961, viz., “containing a full and true disclosure of his income which has not been disclosed before the Assessing Officer”, but it overlooks the expression in Section 245C, viz., “the manner in which such income has been derived”. On a plain construction of both the italicised expressions, what constitutes a case for consideration before the ITSC would be an Assessee making an Application containing a full and true disclosure of the Assessee’s income which has not been disclosed before the AO, and the manner in which such income has been derived. Therefore, the additional amount of income-tax payable in the disclosure will depend on the manner in which such income has been derived by the Assessee. In the case on hand, the Assessee has disclosed the revenue included in the Assessee's
28
gross total income, and, by claiming deductions under the Act, 1961, the net income liable for tax is set out. Once the ITSC admits the case for settlement, the consideration is the return for the assessment year, including deductions. The Report is called for on the Assessee's Application, and there is no gainsaying that, while participating in the Settlement before ITSC, the Revenue allowed a deduction that is otherwise disallowable. The normal presumption is that the Revenue filed its Report on the Assessee's application. Once the matter is concluded under Section 245D(4), the decision attains finality, and the scope of judicial review, in view of the precedents referred to above, is also limited. 24. The Revenue is not without recourse to realise tax on undisclosed income, even in cases filed under Chapter XIX-A of the Act, 1961. The Revenue has the option to move under Section 245D(6) of the Act, 1961 on the grounds of fraud and misrepresentation. The words “fraud and misrepresentation” depend on the circumstances and are to be decided on a case-to-case basis; by making out a case under either head, the ITSC’s Order is reopened, which ultimately leads to the Settlement Order being declared void. The normal assessment procedure is restored or enabled, but not otherwise. If the jurisdiction of the AO under Sections 143(2), 148, 154, etc., is made independent and available for exercise again, the finality attached to the Settlement Commission will be defeated. Parliament did not envisage this course. On the contrary, while reopening the issues before the ITSC is provided for, judicial review by the Constitutional Courts under Articles 226
29
and 32/136 is available, but the AO’s power to reassess the Settlement Order passed by the ITSC is unavailable. 25. In fine, through the mechanism under Chapter XIX-A of the Act, 1961, the Assessee and the Revenue avoid the crust and crumb. To wit, the Revenue avoids the crust by realising the crumb of tax on suppressed or undisclosed income through the Assessee's voluntary disclosure. Similarly, through complete and fair disclosure of suppressed income and entries, the Assessee avoids the crust of penal interest, prosecution, etc., and the crumb offered is payment of tax beforehand. The Revenue and the Assessee must take the Crust and the Crumb together. By operation of Section 245C(3), the Assessee is precluded from withdrawing the Application filed under Section 245C. The Revenue can oppose continuation before the ITSC based on the material and grounds discovered during the search and seizure against the Assessee. The Revenue participates before the ITSC in the Assessee's Application, including any income further disclosed by the Assessee. Therefore, the argument that, after the proceedings before the ITSC attain finality, the regular assessment/re-assessment is still available to the Revenue is contrary to the defining expressions in Sections 245C, 245D(2), 245D(3), and finally 245D(4) of the Act, 1961. The Revenue has to revisit the procedure under Section 245D(6) by making out a case before the ITSC, but not otherwise. Thus, the Assessee and the Revenue are aware of the crust and the crumb in this settlement procedure before the ITSC. Once the crust is avoided and the
30
crumb is accepted, further crust and crumb are not the intention of Chapter XIX-A of the Act, 1961. 26. The Revenue availed the remedy under Section 245D(6) of the Act, 1961 before the ITSC, resulting in the findings recorded in the Order dated 16.12.2011, which has become final. 27. For the reasons stated above, we find no merit in the Appeal. The Appeal fails and is dismissed. 28. Pending application(s), if any, stand disposed of accordingly.
.…………………………J. [S.V.N. BHATTI]
.…………………………J. [N. V. ANJARIA]
New Delhi; September 16, 2026.