
All insights

Can unpaid excise duty on bonded warehouse stock be disallowed under Section 43B?

Unpaid Excise Duty on Bonded Stock Cannot Be Disallowed Under Section 43B

A sugar manufacturer's unpaid excise duty on closing stock kept in a bonded warehouse was added to its taxable income by the Assessing Officer. The Supreme Court held that since the duty was never cla

Litigation India Editorial 28 October 2026 1 min read 2026 INSC 1162

Story

Case at a glance1 / 6

Supreme Court of India

Unpaid Excise Duty on Bonded Stock Not Disallowable Under Section 43B

M/S. Lakshmi Sugar Mills Co. Ltd. vs Commissioner of Income Tax, Delhi-II | 2026 INSC 1162

Court: Supreme Court of India | Date: October 27, 2026Bench: Justice S.V.N. Bhatti and Justice N.V. AnjariaArea of Law: Income Tax — Excise Duty Valuation, Section 43B and Section 145ACivil Appeal No. 8932 of 2013 — Allowed
Unpaid Excise Duty on Bonded Stock Cannot Be Disallowed Under Section 43B · 2026 INSC 11622026-10-28T04:30:35.776431+00:00
The legal question2 / 6

Can Unpaid Excise Duty on Bonded Stock Be Disallowed Under Section 43B?

Core legal dispute between Assessee and Revenue

  • Appellant: Excise duty on bonded warehouse stock had not accrued; no deduction was ever claimed in Profit and Loss Account.
  • Appellant: Exclusive accounting method meant disputed amount was routed through balance sheet, not P&L; Section 43B inapplicable.
  • Respondent: Tax Audit Report itself noted Rs. 69,91,983 as payable; AO was right to disallow the sum.
  • Respondent: High Court correctly found goods were removed and duty was therefore payable.
Unpaid Excise Duty on Bonded Stock Cannot Be Disallowed Under Section 43B · 2026 INSC 11622026-10-28T04:30:35.776431+00:00
Statutory comparison3 / 6

Section 43B vs Section 145A: How They Interact

Income Tax Act, 1961

ProvisionWhat it saysHow the Court applied it
Section 43BDeduction for statutory dues allowed only in the year of actual payment; unpaid amounts disallowed.Court held it cannot disallow amounts never claimed as deductions by the Assessee in P&L Account.
Section 145ANon-obstante clause; mandates inclusive valuation of stocks for duties paid/payable.Tax Auditor certified net profit impact was Nil when both opening and closing stocks valued inclusively on same basis.
When both stocks are valued on the same inclusive basis, the net impact under Section 145A is Nil — making any addition unjustified.
Unpaid Excise Duty on Bonded Stock Cannot Be Disallowed Under Section 43B · 2026 INSC 11622026-10-28T04:30:35.776431+00:00
The Court's reasoning4 / 6

Court's Reasoning: From Audit Remark to Final Order

Step-by-step analysis

  1. 1Step 1: High Court wrongly assumed goods were removed from bonded warehouse — contrary to AO Remand Report, CIT(A) and Tribunal findings.
  2. 2Step 2: Section 43B applies only to disallow amounts actually claimed as deductions; Assessee never debited disputed sum to P&L Account.
  3. 3Step 3: Exclusive accounting method (AS-2) lawfully routes indirect taxes through balance sheet — no deduction claimed, no disallowance possible.
  4. 4Step 4: Tax Auditor's own certificate confirmed Nil net impact on profitability under Section 145A when opening and closing stocks valued uniformly.
  5. 5Step 5: Revenue failed to show where Assessee claimed the allowance; disallowance was illegal and was rightly deleted by CIT(A) and Tribunal.
Unpaid Excise Duty on Bonded Stock Cannot Be Disallowed Under Section 43B · 2026 INSC 11622026-10-28T04:30:35.776431+00:00
The verdict5 / 6

The Verdict

Supreme Court allows the Civil Appeal

  • The Fact: Assessee never claimed Rs. 69,91,983 as a deduction; stock remained in bonded warehouse and goods were not removed.
  • The Law: Section 43B cannot disallow an amount not claimed as deduction; Section 145A net impact was Nil per Tax Auditor's certificate.
  • The Result: High Court's order reversed; CIT(A) and Tribunal orders restoring the deletion of addition are confirmed.
Civil Appeal No. 8932 of 2013 allowed; impugned High Court order set aside; CIT(A) and Tribunal orders restored.
Unpaid Excise Duty on Bonded Stock Cannot Be Disallowed Under Section 43B · 2026 INSC 11622026-10-28T04:30:35.776431+00:00
Why it matters6 / 6

What This Means for Businesses

Practical significance

  • Tax authorities cannot disallow a sum under Section 43B unless the taxpayer actually claimed it as a deduction in accounts.
  • Goods stored in bonded warehouses do not attract excise duty until removed; audit report remarks alone do not create tax liability.
  • Businesses using the exclusive method of accounting for indirect taxes are protected from arbitrary additions to taxable income.
  • High Courts hearing Section 260A appeals must not substitute their own factual findings contrary to the record.
Section 43B can only disallow what was actually claimed — not what was never put through the Profit and Loss Account.
Unpaid Excise Duty on Bonded Stock Cannot Be Disallowed Under Section 43B · 2026 INSC 11622026-10-28T04:30:35.776431+00:00
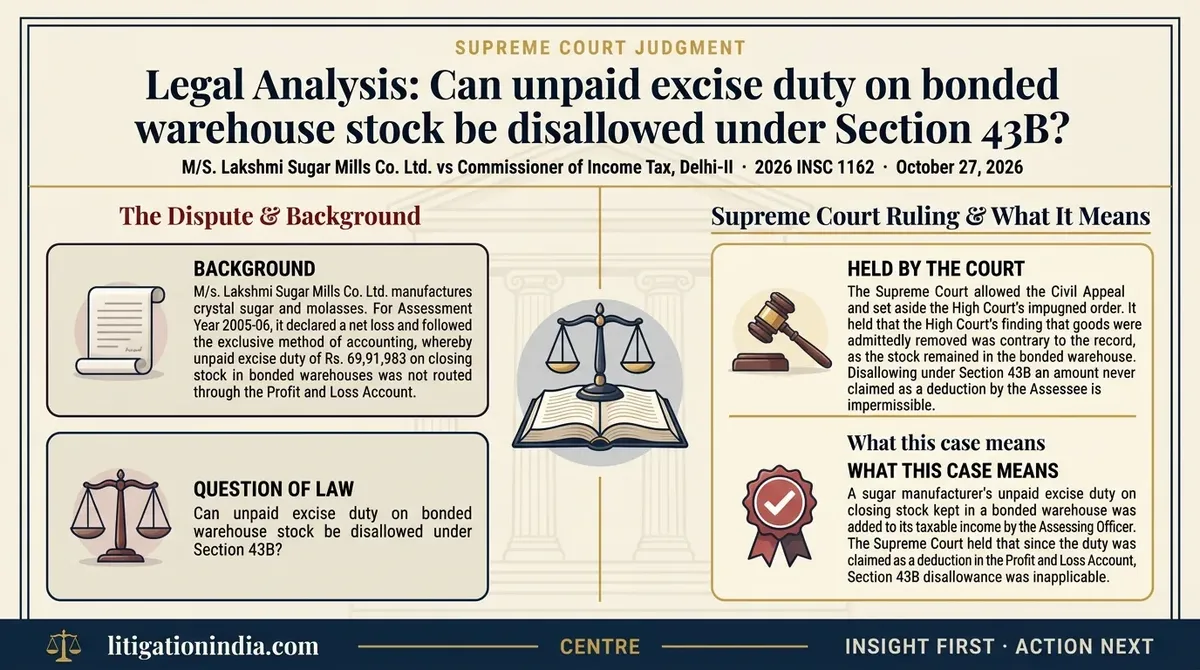
Unpaid Excise Duty on Bonded Stock Cannot Be Disallowed Under Section 43B — infographic summary

What this case means

A sugar manufacturer's unpaid excise duty on closing stock kept in a bonded warehouse was added to its taxable income by the Assessing Officer. The Supreme Court held that since the duty was never claimed as a deduction in the Profit and Loss Account, Section 43B disallowance was inapplicable. The High Court's interference with the Tribunal's findings was set aside.

What the Supreme Court held

The Supreme Court allowed the Civil Appeal and set aside the High Court's impugned order. It held that the High Court's finding that goods were admittedly removed was contrary to the record, as the stock remained in the bonded warehouse. Disallowing under Section 43B an amount never claimed as a deduction by the Assessee is impermissible.

Case: M/S. Lakshmi Sugar Mills Co. Ltd. vs Commissioner of Income Tax, Delhi-II (2026) Citation: 2026 INSC 1162

Want the full legal reasoning, citations and case documents?

Read the full judgment analysis
Lakshmi Sugar Mills
Section 43B
Section 145A
Income Tax Act 1961
excise duty closing stock
disallowance
bonded warehouse
mercantile accounting
sugar manufacturer
exclusive method
Section 43B, Income Tax Act, 1961
Section 145A, Income Tax Act, 1961
Section 139(3), Income Tax Act, 1961
Section 143(2) and Section 142(1), Income Tax Act, 1961