
Story
What this case means
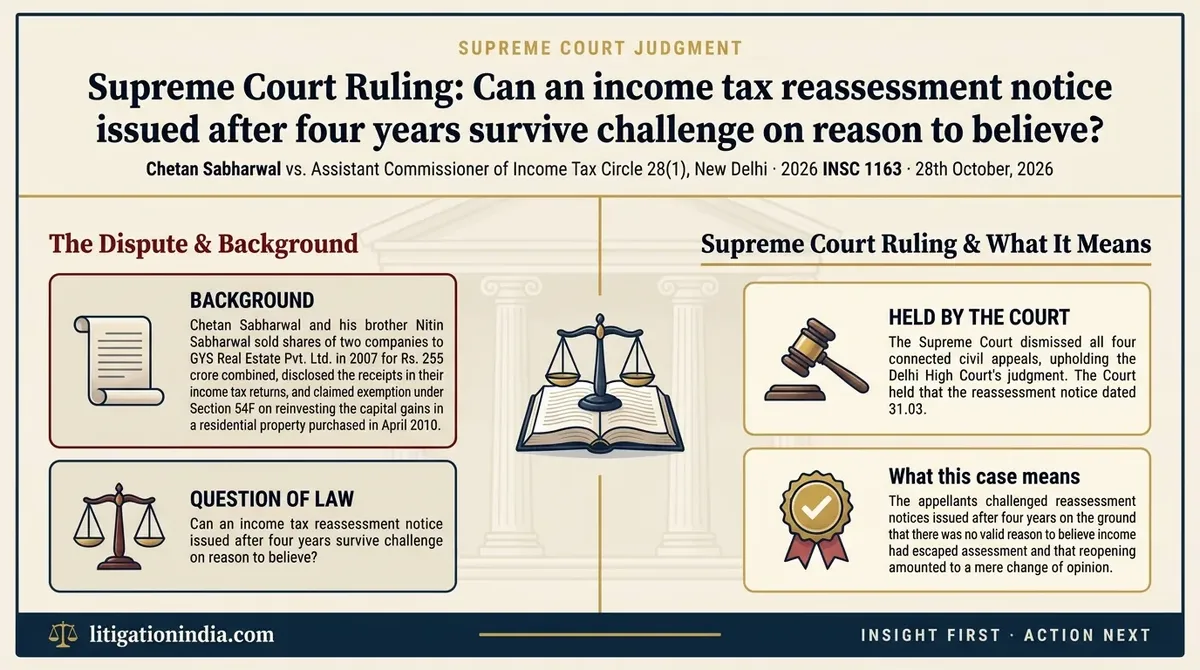
The appellants challenged reassessment notices issued after four years on the ground that there was no valid reason to believe income had escaped assessment and that reopening amounted to a mere change of opinion. The Supreme Court dismissed the appeals, holding that the Investigation Unit report constituted tangible material with a live link to the belief that income had escaped assessment. The judgment authoritatively consolidates the law on reason to believe and change of opinion under Sections 147 and 148 of the Income Tax Act, 1961.
What the Supreme Court held
The Supreme Court dismissed all four connected civil appeals, upholding the Delhi High Court's judgment. The Court held that the reassessment notice dated 31.03.2015 was valid, as the investigation report of the DGIT Investigation Unit, Noida constituted tangible material with a rational nexus and live link to the belief that income had escaped assessment for AY 2008-09 and AY 2009-10. The Court further held that no case of change of opinion was made out in the case of either appellant.
Case: Chetan Sabharwal vs. Assistant Commissioner of Income Tax Circle 28(1), New Delhi (2026) Citation: 2026 INSC 1163
Want the full legal reasoning, citations and case documents?
Read the full judgment analysis