Story
What this case means
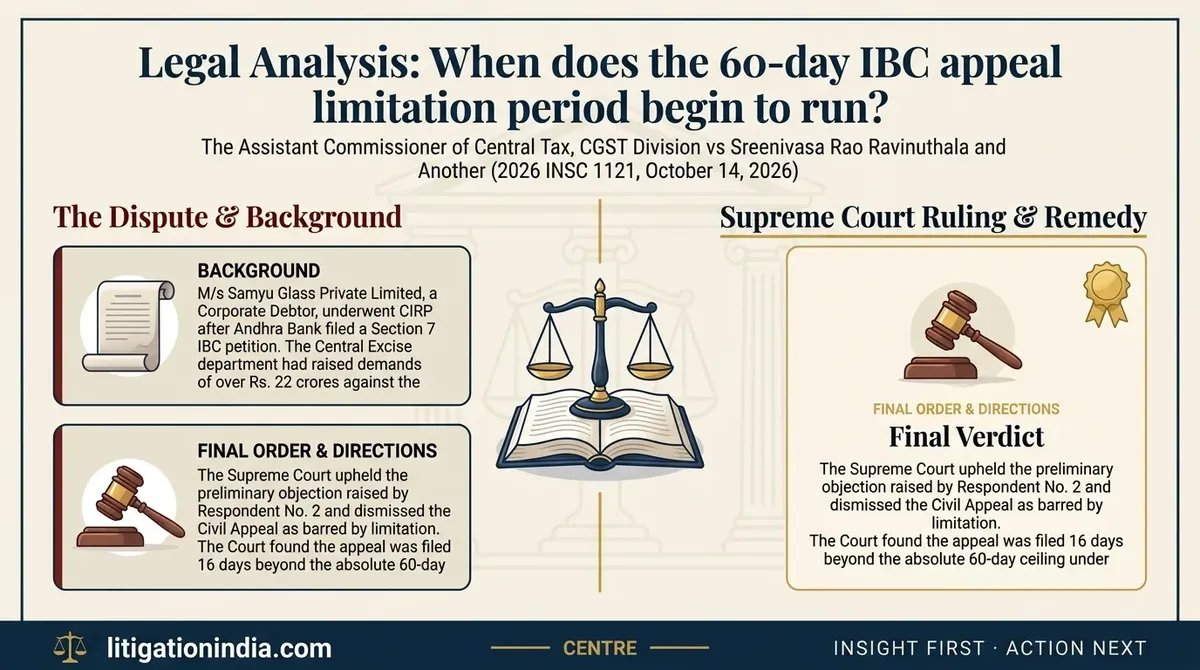
The Central Tax department challenged an approved Resolution Plan under the IBC but filed its appeal to the Supreme Court 16 days beyond the absolute 60-day outer limit under Section 62 of the IBC. The Court held that limitation runs from the date the NCLAT pronounces its order, not from when the appellant chooses to collect a certified copy. The appeal was dismissed as time-barred.
What the Supreme Court held
The Supreme Court upheld the preliminary objection raised by Respondent No. 2 and dismissed the Civil Appeal as barred by limitation. The Court found the appeal was filed 16 days beyond the absolute 60-day ceiling under Section 62 of the IBC, over which no court has jurisdiction to condone delay. No order as to costs was made.
Case: The Assistant Commissioner of Central Tax, CGST Division vs Sreenivasa Rao Ravinuthala and Another (2026) Citation: 2026 INSC 1121
Want the full legal reasoning, citations and case documents?
Read the full judgment analysis