
Story
What this case means
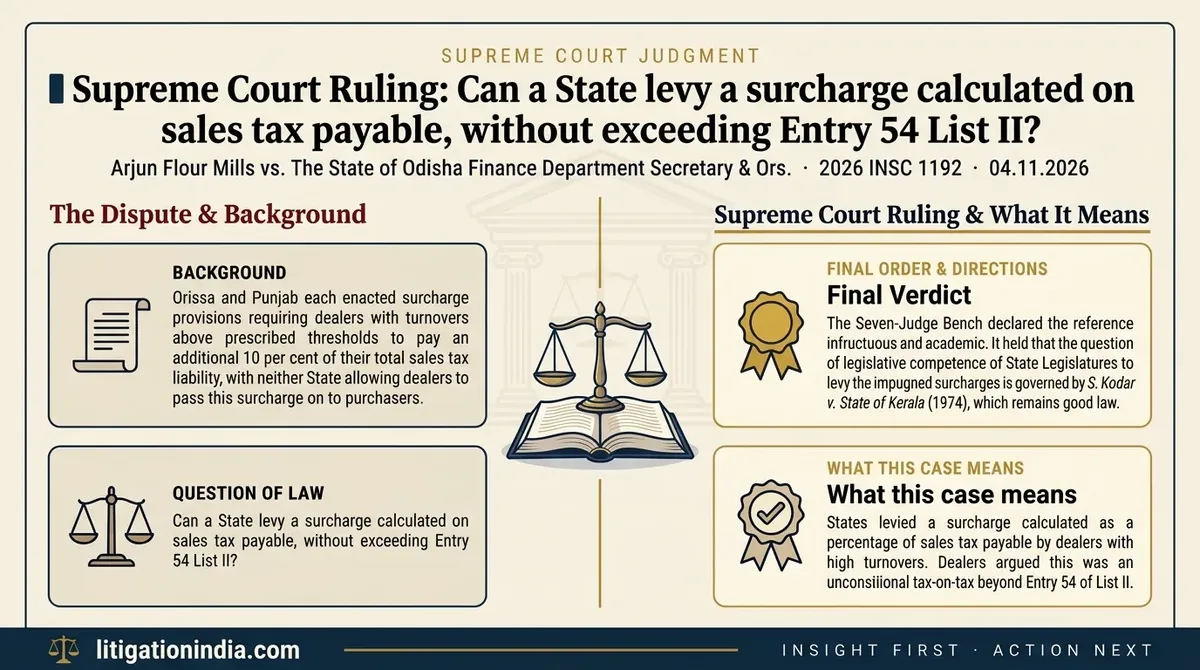
States levied a surcharge calculated as a percentage of sales tax payable by dealers with high turnovers. Dealers argued this was an unconstitutional tax-on-tax beyond Entry 54 of List II. The Seven-Judge Bench held the reference was rendered academic because the perceived conflict no longer existed, and the law was already settled by the Constitution Bench in S. Kodar v. State of Kerala.
What the Supreme Court held
The Seven-Judge Bench declared the reference infructuous and academic. It held that the question of legislative competence of State Legislatures to levy the impugned surcharges is governed by S. Kodar v. State of Kerala (1974), which remains good law. The questions on Section 30-AA of the Punjab General Sales Tax Act and the constitutional validity of the Punjab Social Security Act, 2000 cess were left open for appropriate regular Benches, as were all individual contentions relating to assessments, periods of levy, and consequential reliefs.
Case: Arjun Flour Mills vs. The State of Odisha Finance Department Secretary & Ors. (2026) Citation: 2026 INSC 1192
Want the full legal reasoning, citations and case documents?
Read the full judgment analysis