
Story
What this case means
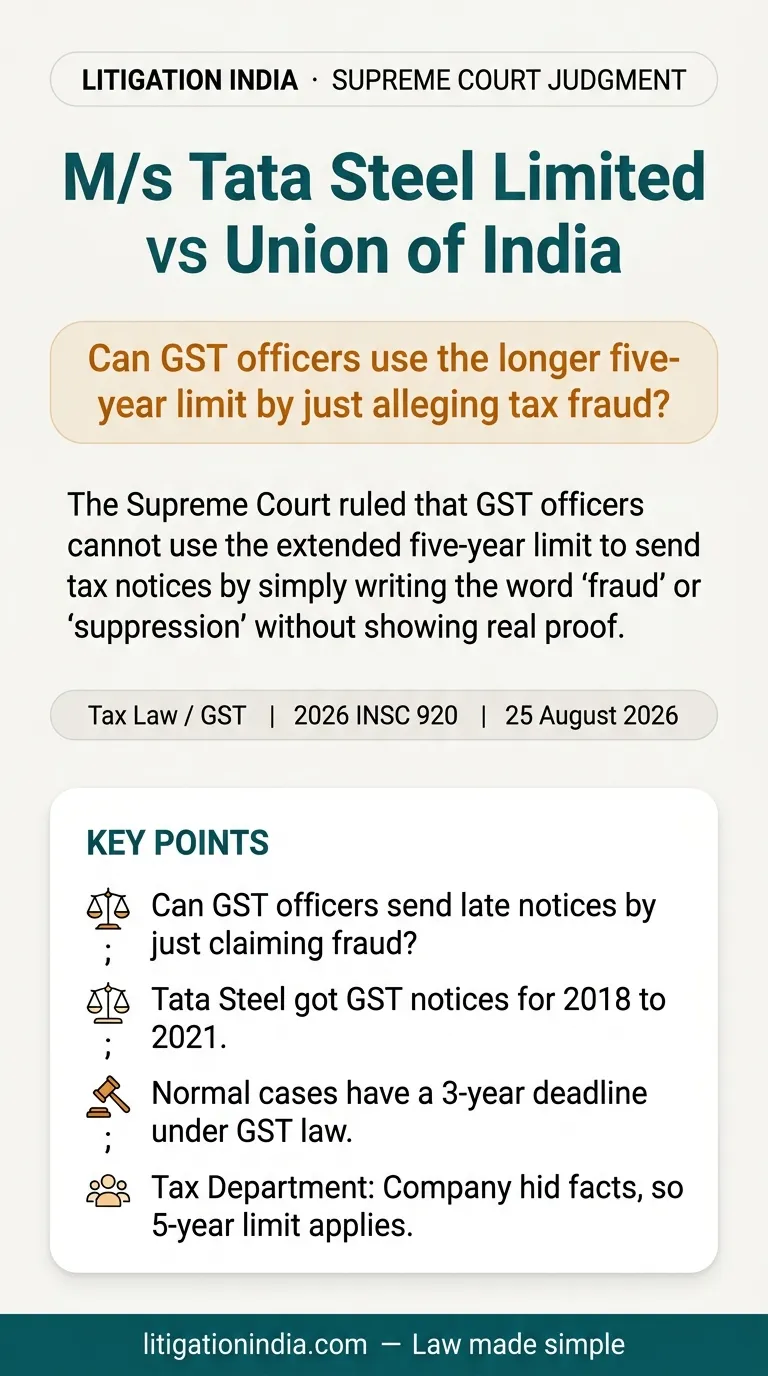
The Supreme Court ruled that GST officers cannot use the extended five-year limit to send tax notices by simply writing the word 'fraud' or 'suppression' without showing real proof.
What the Supreme Court held
The Supreme Court cancelled the tax notices and the final tax demand order because they lacked solid facts to prove fraud. However, the Court allowed the department to issue fresh notices before February 28, 2027, provided they have clear, genuine evidence of fraud or suppression.
Case: M/s Tata Steel Limited vs Union of India (2026) Citation: 2026 INSC 920
Want the full legal reasoning, citations and case documents?
Read the full judgment analysisGST Notice
Tax Deadline
Fraud Allegation
Input Tax Credit
Tax Law / GST
Supreme Court legal news
Supreme Court judgment today
latest Supreme Court news