
All insights

Can a State Government accept a gift of temple inam land from a temporary trustee?

Gift of Temple Inam Land to Government Declared Void Under Tamil Nadu Endowments Act

A temporary trustee of a Tamil Nadu temple gifted inam land to the State Government for a Taluk Office without legal authority. The Supreme Court declared the gift deed void under Section 41(1) of the

Litigation India Editorial 16 October 2026 1 min read 2026 INSC 1144

Story

Case at a glance1 / 6

Supreme Court of India

Can the State Accept a Gift of Temple Inam Land?

K. Ramalingam & Ors. v. Government of Tamil Nadu & Ors. | 2026 INSC 1144

Court: Supreme Court of India | Date: October 16, 2026Bench: Justice Pamidighantam Sri Narasimha and Justice Alok AradheArea of Law: Religious Endowments / Temple Trust Property / AlienationTemporary trustee gifted temple inam land to Tamil Nadu Government for a Taluk Office without legal authority
Temple property belongs to the deity — no trustee or State authority can give it away gratuitously.
Gift of Temple Inam Land to Government Declared Void Under Tamil Nadu Endowments Act · 2026 INSC 11442026-10-16T13:37:58.942838+00:00
The legal question2 / 6

Can a Temporary Trustee Gift Temple Inam Land to the Government?

Core legal issue decided by the Supreme Court

  • Appellant: Gift deed violates Section 34/Section 41 of the 1959 Act; temporary trustee has no such authority; registration barred by Section 22-A of the Registration Act, 1908.
  • Respondent (State): Land has vested absolutely in the Government; Taluk Office serves genuine public need; Section 34 does not mention gift.
  • Respondent (Temporary Trustee): Transfer was in public interest with devotees' unanimous approval; Section 34 does not prohibit gifts.
  • Amicus Curiae: A gift, being without consideration, can never be necessary or beneficial to the donor institution; Section 41 prohibits and makes it void ab initio.
Gift of Temple Inam Land to Government Declared Void Under Tamil Nadu Endowments Act · 2026 INSC 11442026-10-16T13:37:58.942838+00:00
Statutory comparison3 / 6

Section 34 vs Section 41: Alienation of Temple Property

How the 1959 Act treats general religious institution property vs inam property

Legal SubjectSection 34 (General Property)Section 41 (Inam Property)
Transactions coveredExchange, sale, mortgage, long leaseExchange, gift, sale, mortgage, long lease
Gifts covered?No — gift not mentionedYes — gift explicitly included and void
Possibility of sanctionCommissioner can sanction if necessary/beneficialGovernment can sanction any transaction except gifts
Effect of non-sanctionNull and voidNull and void; gift can never be sanctioned
Applies to this case?No — excluded by Section 34(5)Yes — land is inam property
A gift of inam temple property is void ab initio — no sanction by any authority can cure it.
Gift of Temple Inam Land to Government Declared Void Under Tamil Nadu Endowments Act · 2026 INSC 11442026-10-16T13:37:58.942838+00:00
The Court's reasoning4 / 6

Court's Reasoning: Step by Step

From the gift deed to the final declaration of nullity

  1. 1Step 1: State's own affidavit confirmed the land is inam property under Inam Title Deed No. 388 — Section 41, not Section 34, governs.
  2. 2Step 2: Section 41(1) covers gifts of inam property and declares them void; unlike Section 34, it permits no sanction for gifts whatsoever.
  3. 3Step 3: Sections 27 and 28 bind every trustee to act prudently — a gratuitous gift confers no benefit on the trust and violates fiduciary duty.
  4. 4Step 4: State as custodian under 1959 Act cannot become owner of temple property; sovereign status does not override custodial obligations.
  5. 5Step 5: Registration under the Registration Act, 1908 (Section 22-A) cannot validate what the 1959 Act declares void — gift is null and void ab initio.
Gift of Temple Inam Land to Government Declared Void Under Tamil Nadu Endowments Act · 2026 INSC 11442026-10-16T13:37:58.942838+00:00
The verdict5 / 6

Supreme Court's Final Decision

High Court order set aside; Gift Deed declared void

  • The Fact: Temporary trustee gifted inam temple land to Tamil Nadu Government without authority; Taluk Office constructed on it from public funds.
  • The Law: Section 41(1) of the 1959 Act renders gifts of inam property void ab initio with no possibility of sanction; Section 22-A of Registration Act, 1908, also bars such registration.
  • The Result: Gift Deed declared null and void; lease rent enhanced to Rs. 31,000/month from 08.03.2019; arrears payable within three months; State directed to pay Rs. 1,00,000 costs to Temple.
Gift Deed dated 30.08.2017 declared null and void; lease rent enhanced to Rs. 31,000 per month from 08.03.2019; State to pay Rs. 1,00,000 costs.
Gift of Temple Inam Land to Government Declared Void Under Tamil Nadu Endowments Act · 2026 INSC 11442026-10-16T13:37:58.942838+00:00
Why it matters6 / 6

Why This Judgment Matters

Practical significance for temple communities and devotees

  • Temple property belongs to the deity in perpetuity — no trustee, government official or public purpose can override this dedication.
  • Even the State, as statutory custodian of religious institutions, cannot receive temple land as a gift; it remains bound by the 1959 Act.
  • Devotees and worshippers have standing to challenge illegal alienation of temple property, protecting community religious heritage.
  • All future alienations or leases of religious institution property must strictly follow Sections 34, 34-A and 41 of the 1959 Act or face nullity.
What is dedicated to a deity remains dedicated forever — no State official or trustee can give it away, whatever the public purpose.
Gift of Temple Inam Land to Government Declared Void Under Tamil Nadu Endowments Act · 2026 INSC 11442026-10-16T13:37:58.942838+00:00
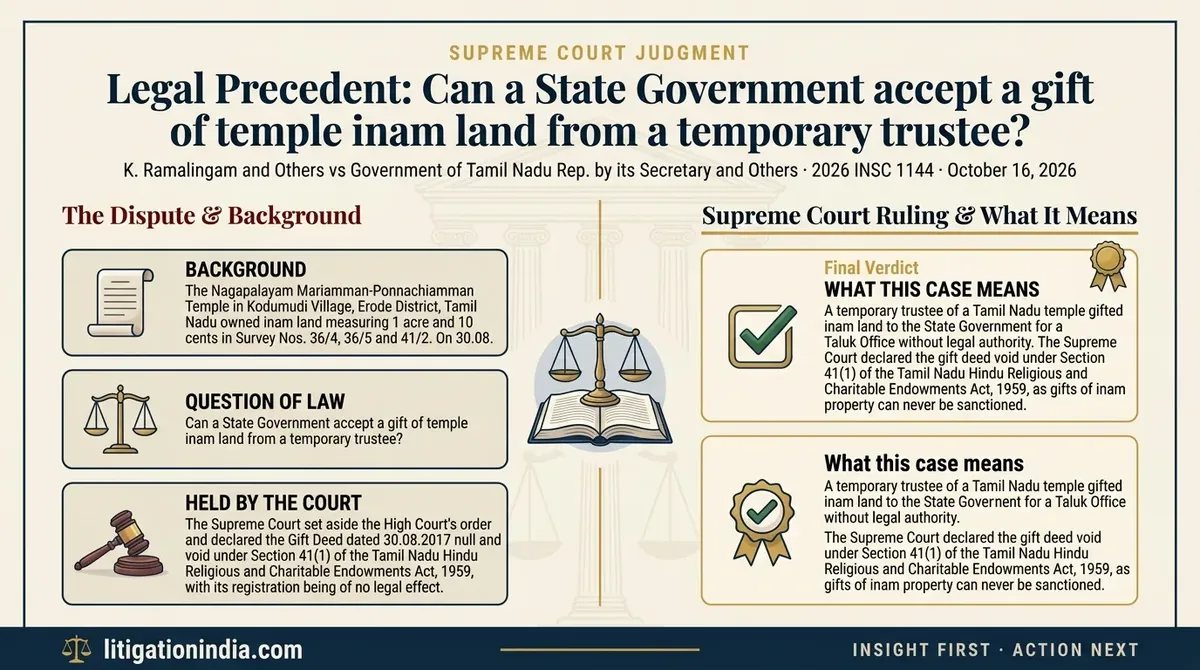
Gift of Temple Inam Land to Government Declared Void Under Tamil Nadu Endowments Act — infographic summary

What this case means

A temporary trustee of a Tamil Nadu temple gifted inam land to the State Government for a Taluk Office without legal authority. The Supreme Court declared the gift deed void under Section 41(1) of the Tamil Nadu Hindu Religious and Charitable Endowments Act, 1959, as gifts of inam property can never be sanctioned. This case affirms that temple property belongs to the deity and no trustee or State authority can give it away without legal sanction.

What the Supreme Court held

The Supreme Court set aside the High Court's order and declared the Gift Deed dated 30.08.2017 null and void under Section 41(1) of the Tamil Nadu Hindu Religious and Charitable Endowments Act, 1959, with its registration being of no legal effect. While declining to annul the existing lease since a Taluk Office had been constructed on the land, the Court enhanced the lease rent to Rs. 31,000 per month from 08.03.2019 and directed payment of all arrears within three months. The State was also directed to pay costs of Rs. 1,00,000 to the Temple and to strictly comply with Sections 34, 34-A and 41 of the 1959 Act for all future transactions involving temple property.

Case: K. Ramalingam and Others vs Government of Tamil Nadu Rep. by its Secretary and Others (2026) Citation: 2026 INSC 1144

Want the full legal reasoning, citations and case documents?

Read the full judgment analysis
temple property
inam land
gift deed
Tamil Nadu Hindu Religious and Charitable Endowments Act 1959
Section 41
null and void
trustee alienation
religious institution
Nagapalayam Mariamman-Ponnachiamman Temple
K. Ramalingam
Government of Tamil Nadu
charitable endowments
Section 41(1), Tamil Nadu Hindu Religious and Charitable Endowments Act, 1959
Section 34(1) and Section 34(5), Tamil Nadu Hindu Religious and Charitable Endowments Act, 1959