Story
What this case means
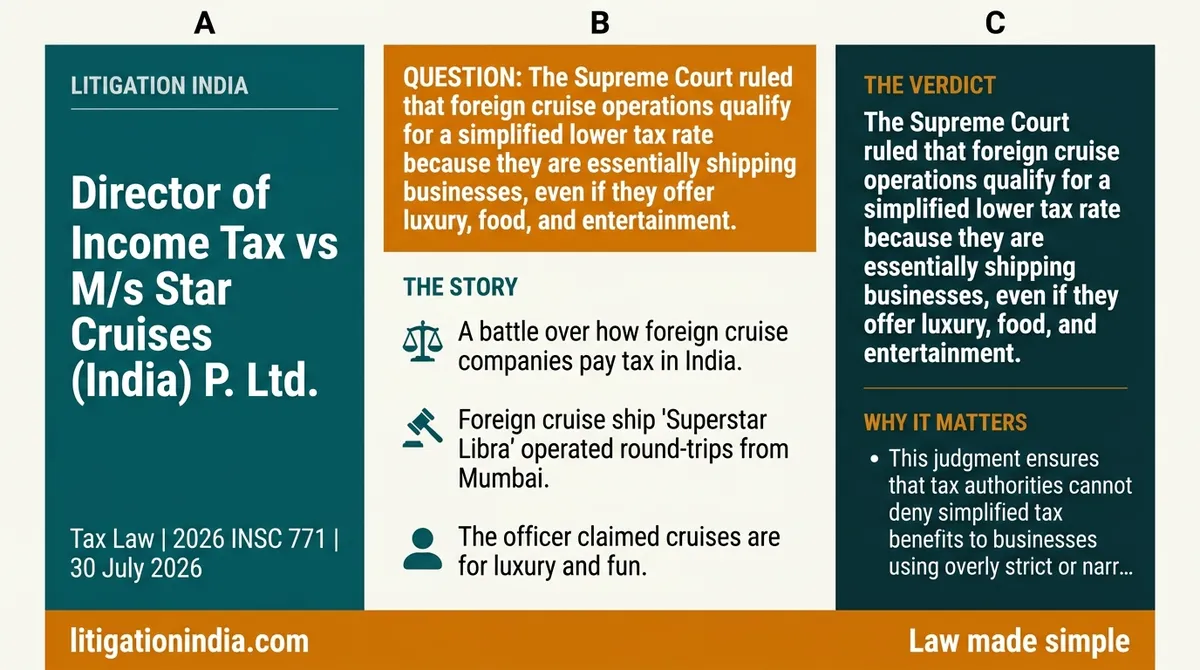
This case was about whether luxury cruise ships should pay a higher tax as entertainment businesses or a lower simplified tax as shipping businesses. The Supreme Court decided that offering food and entertainment on a cruise does not stop it from being a shipping transport business. This decision ensures that the tax department cannot use overly strict definitions to deny simplified tax benefits to businesses.
What the Supreme Court held
The Supreme Court dismissed the tax department's appeals, confirming that providing extra services on a voyage does not disqualify a cruise from being classified as a transport and shipping business under the law. The cruise operator was allowed to use the simplified 7.5% tax rate.
Case: Director of Income Tax vs M/s Star Cruises (India) P. Ltd. (2026) Citation: 2026 INSC 771
Want the full legal reasoning, citations and case documents?
Read the full judgment analysis