
All insights

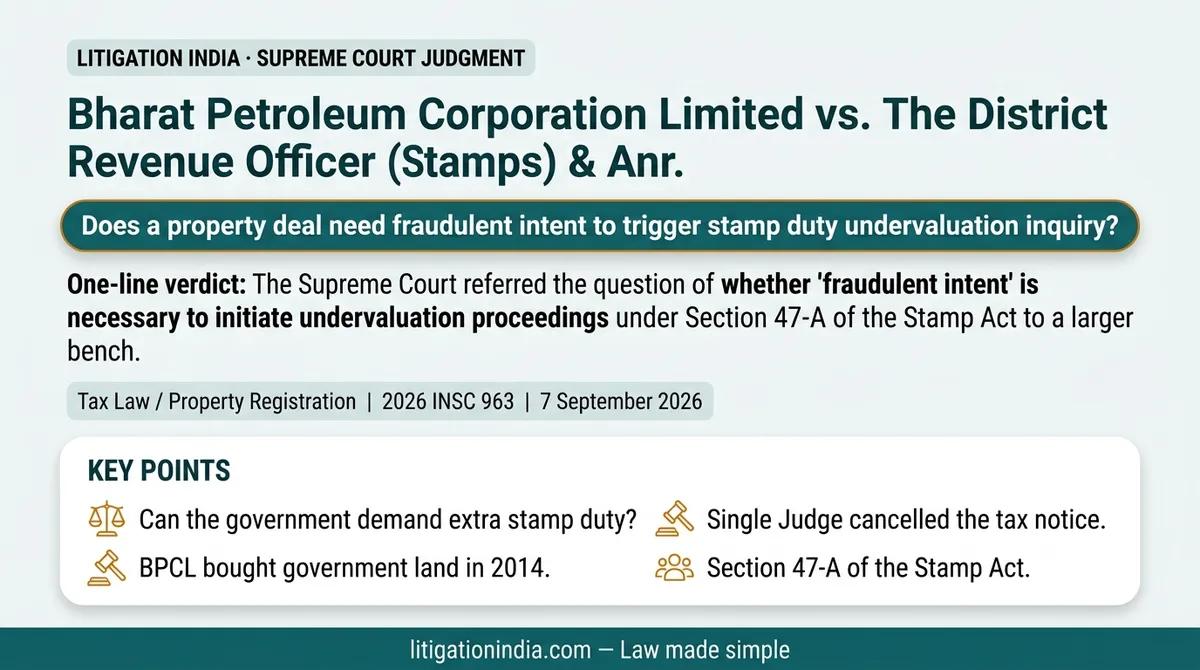
Does a property deal need fraudulent intent to trigger stamp duty undervaluation inquiry?

Bharat Petroleum Corporation Limited vs. The District Revenue Officer (Stamps) & Anr.

The Supreme Court referred the question of whether 'fraudulent intent' is necessary to initiate undervaluation proceedings under Section 47-A of the Stamp Act to a larger bench.

Litigation India Editorial 7 September 2026 1 min read 2026 INSC 963

Story

Key points1 / 7

Property Valuation vs. Stamp Duty

  • Can the government demand extra stamp duty?
  • Does actual sale price overrule circle rate?
  • A dispute between BPCL and Tamil Nadu.
Bharat Petroleum Corporation Limited vs. The District Revenue Officer (Stamps) & Anr. · 2026 INSC 9632026-09-07T17:34:51.409041+00:00
Key points2 / 7

The Land Deal and Notice

  • BPCL bought government land in 2014.
  • Paid stamp duty on actual purchase price.
  • Registrar demanded extra duty based on circle-rate.
Bharat Petroleum Corporation Limited vs. The District Revenue Officer (Stamps) & Anr. · 2026 INSC 9632026-09-07T17:34:51.409041+00:00
Key points3 / 7

Conflicting High Court Decisions

  • Single Judge cancelled the tax notice.
  • Said 'fraudulent intent' is required for inquiry.
  • Division Bench restored the notice for investigation.
Bharat Petroleum Corporation Limited vs. The District Revenue Officer (Stamps) & Anr. · 2026 INSC 9632026-09-07T17:34:51.409041+00:00
Key points4 / 7

The Law Under Review

  • Section 47-A of the Stamp Act.
  • Plain text does not mention 'fraudulent intent'.
  • Past ruling (V.N. Devadoss) added this condition.
Bharat Petroleum Corporation Limited vs. The District Revenue Officer (Stamps) & Anr. · 2026 INSC 9632026-09-07T17:34:51.409041+00:00
Key points5 / 7

Why SC Doubts Past Ruling

  • Tax laws must be read literally.
  • Honest buyers get dragged into character inquiries.
  • Tax evaders easily escape if fraud proof is required.
Bharat Petroleum Corporation Limited vs. The District Revenue Officer (Stamps) & Anr. · 2026 INSC 9632026-09-07T17:34:51.409041+00:00
Key points6 / 7

Referred to a Larger Bench

  • Two-judge bench cannot overrule three-judge bench.
  • Referred the legal questions to Chief Justice.
  • Larger bench will decide the final rule.
Bharat Petroleum Corporation Limited vs. The District Revenue Officer (Stamps) & Anr. · 2026 INSC 9632026-09-07T17:34:51.409041+00:00
Key points7 / 7

Impact on Common Buyers

  • Defines how circle rates affect honest deals.
  • Clarifies when government can demand extra duty.
  • Brings clarity to future property registrations.
Bharat Petroleum Corporation Limited vs. The District Revenue Officer (Stamps) & Anr. · 2026 INSC 9632026-09-07T17:34:51.409041+00:00
Bharat Petroleum Corporation Limited vs. The District Revenue Officer (Stamps) & Anr. — infographic summary

What this case means

The Supreme Court referred the question of whether 'fraudulent intent' is necessary to initiate undervaluation proceedings under Section 47-A of the Stamp Act to a larger bench.

What the Supreme Court held

The Supreme Court doubted the correctness of its own earlier judgment which required 'fraudulent intent' to investigate property undervaluation. Since that earlier decision was by a three-judge bench, the Court referred the issue to a larger bench for a final decision.

Case: Bharat Petroleum Corporation Limited vs. The District Revenue Officer (Stamps) & Anr. (2026) Citation: 2026 INSC 963

Want the full legal reasoning, citations and case documents?

Read the full judgment analysis
stamp duty evasion
undervaluation of property
Section 47-A Stamp Act
guideline value vs market value
show cause notice writ petition
fraudulent intent stamp duty
can government demand extra stamp duty
property valuation dispute
Tax Law / Property Registration
Supreme Court legal news
Supreme Court judgment today
latest Supreme Court news